Insights
Investor insights from Finresi.
Plain-spoken articles on how real estate debt works, what our platform protections actually do, and how to decide which way of investing fits your goals.
 Insights
September 23, 2026
Navigating Inflation: Why First-Lien Real Estate Debt Can Be a Strategic Hedge
First-lien real estate debt resets frequently with market rates, making it one of the few fixed-income strategies that can preserve purchasing power during prolonged inflation. Learn how rate cycles shape real estate debt returns and why private lending is gaining ground.
Read article Insights
September 22, 2026
How the 2026 Interest Rate Environment Shapes Real Estate Debt Returns
In 2026, private real estate loans yield 9%–13% annually, shaped by years of Fed tightening and selective easing. Learn how rate movements directly compress or expand real estate debt returns for disciplined investors.
Read article Insights
September 21, 2026
The Finresi Secondary Market: How We Provide a Liquidity Option for Investors
Illiquidity is the biggest real estate debt investment risk for accredited investors. The Finresi secondary market offers a structured peer-to-peer transfer system so you can exit positions before loan maturity.
Read article Insights
September 18, 2026
Understanding Loan-to-Value (LTV): A Core Metric for Debt Investors
Loan-to-value ratio is the cornerstone metric for assessing real estate debt investment risk. This guide breaks down how LTV works, why the equity cushion matters, and what accredited investors should watch for in underwriting.
Read article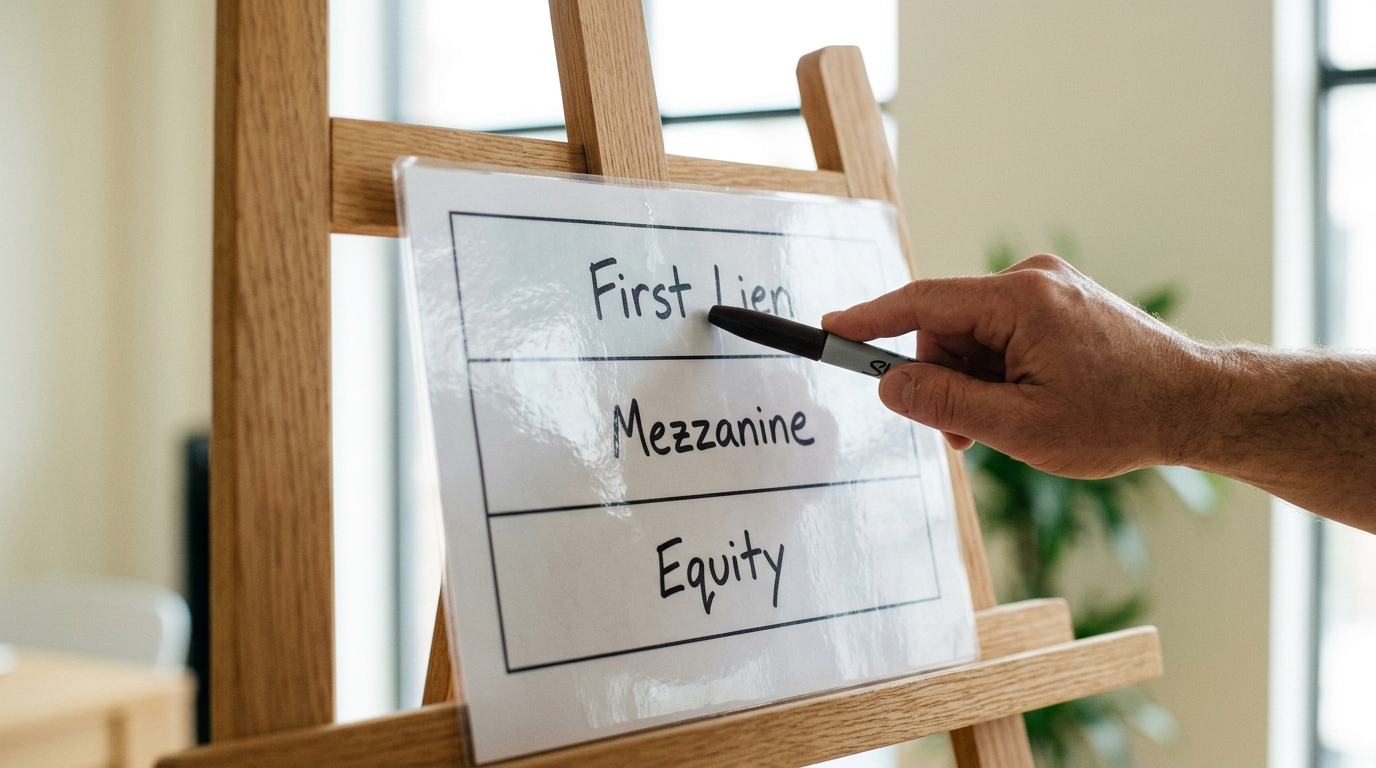 Insights
September 17, 2026
First-Lien Position: How Collateral Protects Your Principal Investment
First-lien position places your investment at the front of the repayment queue, giving you priority over all junior creditors in a default. Understanding this structure is essential for evaluating real estate debt investment risk.
Read article Insights
September 16, 2026
Inside Finresi’s Underwriting: The 25-Point Checklist for Every Loan
Finresi stress-tests every loan against a 25-point underwriting checklist spanning borrower credit, property valuation, loan structure, market conditions, and exit strategy. Here is how each category shapes your real estate debt investment risk profile.
Read article Insights
September 16, 2026
What is an Accredited Investor in 2026? The Official Requirements & How to Verify
Accredited investor status unlocks private real estate debt funds targeting 8–12% annual returns. Learn the 2026 SEC requirements and how to verify your eligibility before you invest.
Read article Insights
September 15, 2026
Beyond LTV: 5 Other Risk Factors to Analyze in a Real Estate Loan Note
Loan-to-value ratio is just the starting point. Learn the five additional real estate debt investment risk factors, including borrower financial strength, market absorption, and exit strategy viability, that determine whether a loan note performs or fails.
Read article Insights
September 14, 2026
Individual Notes vs. The Finresi Fund: Which is Right for Your Portfolio?
Finresi gives accredited investors two paths into real estate debt: hands-on Individual Notes or the diversified Finresi Fund. Here is how to decide which structure fits your capital size and goals.
Read article Insights
September 14, 2026
Understanding Default Scenarios in Real Estate Debt Investing: What Happens Next?
A borrower default does not mean total loss for debt investors. This guide explains the structured recovery process, how lien position determines what you recover, and what every accredited investor should know about real estate debt investment risk.
Read article Insights
September 11, 2026
The Finresi Investment Process: From Account Setup to First Return
Finresi gives accredited investors access to first lien real estate debt targeting 8–12% annualized returns, with a $5,000 minimum. This guide covers every step from account approval to your first funded position.
Read article Insights
September 11, 2026
How is Income from Real Estate Debt Taxed? A Plain-English Explanation
Interest income from real estate debt is taxed as ordinary income, not at preferential capital gains rates. This guide explains IRS classifications, deductions, and account strategies to manage your tax exposure.
Read article