Insights · September 16, 2026
What is an Accredited Investor in 2026? The Official Requirements & How to Verify
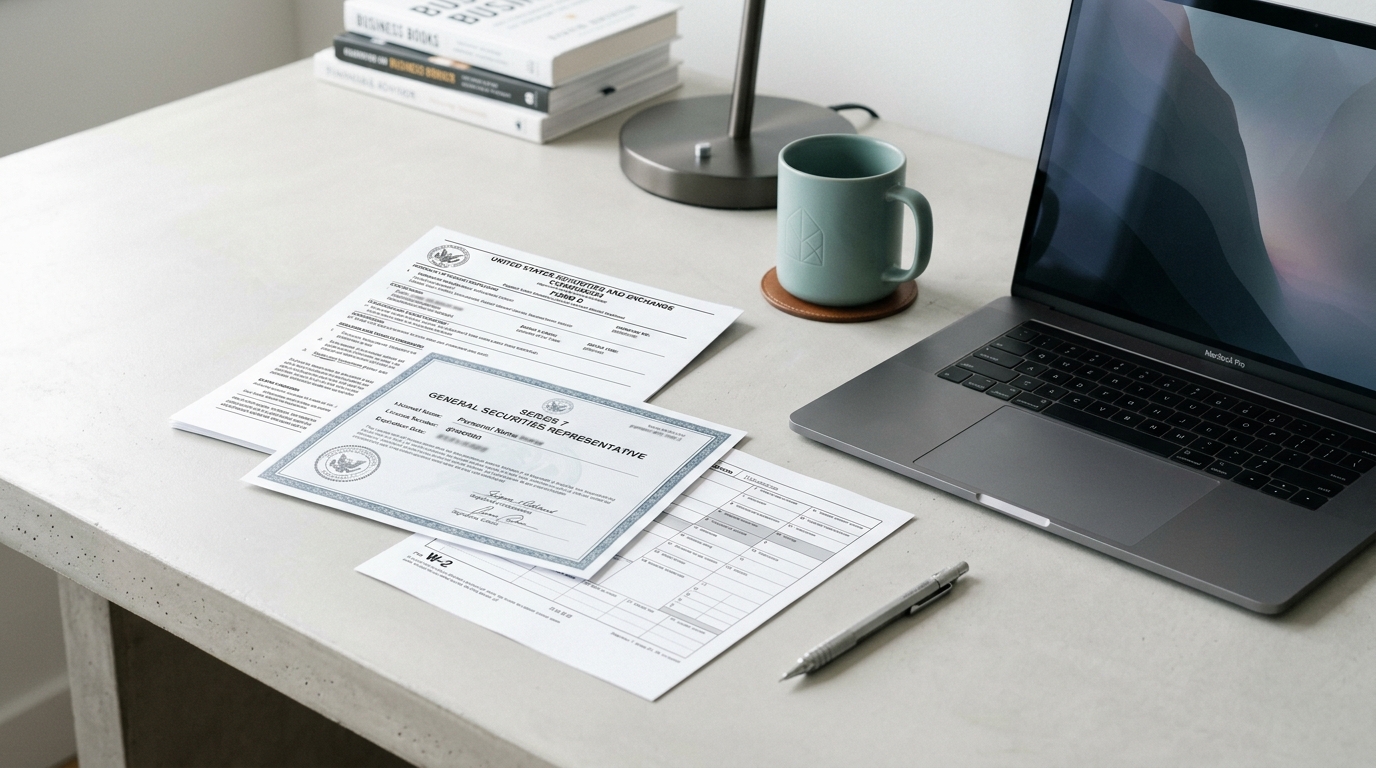
An accredited investor in 2026 is an individual who meets at least one of the following SEC thresholds: a net worth exceeding $1 million (excluding primary residence), annual income above $200,000 individually or $300,000 jointly for the past two years with reasonable expectation of the same, or a qualifying professional certification such as a Series 7, Series 65, or Series 82 license. Meeting any single criterion qualifies you.
Why Accredited Investor Status Matters for Real Estate Debt Investing
The Securities and Exchange Commission created the accredited investor definition to gate access to higher-risk, higher-return private offerings that are exempt from standard registration requirements under Regulation D. Real estate debt funds, private mortgage lending vehicles, and first lien position investments all fall under this exemption category.
For investors seeking passive income through real estate debt, accredited status unlocks a category of investment that publicly traded REITs and savings accounts simply cannot replicate. Real estate debt funds offering first lien position loans regularly target returns in the 8–12% annual range, with the underlying collateral securing your position ahead of equity holders. That structural protection is why accredited-only access exists: the SEC assumes investors at this wealth threshold have sufficient financial sophistication to evaluate the risks themselves.
The practical consequence is significant. Without accredited status, you are legally excluded from platforms like Finresi and comparable private real estate lending vehicles. Verifying your status before you attempt to invest saves time and prevents a frustrating dead end at the final funding step.
The Full 2026 Accredited Investor Requirements
The SEC most recently expanded the accredited investor definition in 2020, and those rules remain in force through 2026. The qualifying pathways are:
- Net worth test: Individual or joint net worth exceeding $1 million, calculated without including the value of your primary residence. Outstanding mortgage debt on that residence reduces your qualifying net worth if it exceeds the home's fair market value.
- Income test (individual): Earned income exceeding $200,000 in each of the two most recent calendar years, with a reasonable expectation of reaching the same level in the current year.
- Income test (joint): Combined income with a spouse or spousal equivalent exceeding $300,000 in each of the two most recent years, with the same forward expectation.
- Professional certification: Holding in good standing a Series 7 (General Securities Representative), Series 65 (Investment Adviser Representative), or Series 82 (Private Securities Offerings Representative) license issued by FINRA.
- Knowledgeable employee: Employees of a private fund (such as executive officers, directors, or investment staff) qualify for that specific fund's offerings based on their role.
- Entity-level qualification: Trusts, LLCs, and corporations with total assets exceeding $5 million, and entities in which all equity owners are independently accredited, also qualify.
The professional certification pathway is notable because it has no income or wealth floor. A licensed Series 65 holder with modest income qualifies, which opened meaningful access to a new demographic of financially sophisticated professionals beginning in 2021.
How Verification Actually Works
Issuers of Regulation D offerings are legally required to take reasonable steps to verify accredited investor status. Accepting a self-certification checkbox alone is no longer sufficient for most Rule 506(c) offerings. Here is what that verification process looks like in practice when you invest through a platform like Finresi:
- Document submission: You upload two years of federal tax returns (W-2s, 1099s, or Schedule C) to satisfy the income test, or a recent brokerage or bank statement alongside a credit report to satisfy the net worth test.
- Third-party verification letter: A CPA, licensed attorney, registered investment adviser, or broker-dealer can issue a written confirmation of your status. Most platforms accept letters dated within 90 days.
- License verification: If you qualify via professional certification, FINRA's BrokerCheck database is used to confirm your license is active. No income documentation is required.
- Repeat verification: Most platforms require re-verification on a 12-month or 24-month cycle, depending on the offering structure.
Finresi uses a streamlined digital verification workflow that processes most submissions within 48–72 hours. You do not need to mail original documents. Scanned copies and e-signatures are accepted under current federal electronic records standards.
How to Invest in Real Estate Debt Once You Qualify
After verification, the investment process for real estate debt has four concrete steps that differ meaningfully from buying a publicly traded asset.
Step 1: Select your loan exposure. Platforms like Finresi present individual loan opportunities or pooled fund shares. Individual loans list the property address, borrower profile, loan-to-value (LTV) ratio, interest rate, and term. A first lien position loan at 65% LTV on a $1.2 million property means the outstanding loan balance is $780,000 and you stand first in line for repayment if the borrower defaults. Pooled fund shares spread your capital across multiple loans, which reduces single-loan concentration risk.
Step 2: Review the offering documents. Private placement memorandums (PPMs) contain the material terms: target returns, fee structure, redemption policies, and risk disclosures. Read the sections on default procedures and how losses are allocated before committing capital. First lien investors get satisfied before second lien holders and equity investors in any liquidation, but the time to resolution on a defaulted loan can range from 90 days to 18 months depending on the state's foreclosure laws.
Step 3: Fund your investment. Wire transfers and ACH are the standard funding methods. Minimum investment thresholds vary by platform and offering structure. Finresi's minimums are designed for individual accredited investors, not just institutional capital.
Step 4: Receive distributions. Real estate debt investments typically distribute interest monthly or quarterly, directly to your linked bank account. Unlike equity investments, you are not waiting for a property to sell to realize income. The loan's contractual interest rate drives your return, making income projections substantially more predictable than dividend-dependent equity strategies.
Real Estate Debt vs. Other Accredited Investment Options
| Investment Type | Typical Target Return | Capital Position | Income Predictability | Liquidity |
|---|---|---|---|---|
| First Lien Real Estate Debt | 8–12% annually | Senior secured | High (contractual rate) | Low (6–24 month terms) |
| Private Equity Real Estate | 12–20% (projected) | Equity (last in line) | Low (depends on sale/appreciation) | Very low (3–7 year hold) |
| Public REIT | 4–8% dividend yield | Equity | Moderate | High (exchange-traded) |
| Investment-Grade Corporate Bonds | 4–6% annually | Senior unsecured | High (coupon rate) | High (secondary market) |
| High-Yield Savings / CDs | 3–5% annually | N/A | High | High to moderate |
The table illustrates a core trade-off: first lien real estate debt sits in a middle band where contractual income predictability is high, capital protection is structurally superior to equity, and returns meaningfully exceed investment-grade bonds, in exchange for reduced liquidity. Investors who do not need immediate access to deployed capital and prioritize consistent income over speculative appreciation have strong structural reasons to allocate to this category.
Risk Factors Accredited Investors Must Evaluate
First lien position protects you structurally, but it does not eliminate risk. Four specific factors require due diligence before any real estate debt commitment:
- LTV ratio: A 70% LTV provides a 30% equity cushion before your principal is at risk. LTVs above 80% warrant deeper scrutiny of the borrower profile and property market.
- Property type concentration: Single-family residential, multifamily, and commercial properties carry different demand cycles. Concentrated exposure to one property type in one geographic market increases volatility.
- Borrower credit and experience: Fix-and-flip borrowers with three completed projects in the past two years represent a materially different risk profile than first-time developers. Review the platform's underwriting criteria.
- State foreclosure timeline: Judicial foreclosure states like New York and Florida require court proceedings that extend default resolution to 12–24 months. Non-judicial states like Georgia and Texas typically resolve defaults in 90–180 days. This timeline directly affects how long your capital is tied up if a loan goes into default.
Accredited Investor Real Estate Debt FAQ
Can I qualify as an accredited investor without meeting the income threshold?
Yes. The net worth test (over $1 million excluding primary residence) and the professional certification pathway (active Series 7, 65, or 82 license) both qualify you independently of income. You only need to satisfy one criterion.
How long does accredited investor verification take on Finresi?
Finresi's digital verification process typically completes within 48–72 hours of document submission. A third-party verification letter from a CPA or attorney is the fastest path if your documents are already organized.
What does first lien position mean for my investment safety?
First lien position means your loan is secured by a recorded mortgage or deed of trust that takes priority over all other claims on the property. In a default, the first lien holder is paid from the proceeds of any property sale before second lien holders, junior creditors, or equity owners receive anything.
Is real estate debt income taxed as ordinary income or capital gains?
Interest income from real estate debt investments is generally taxed as ordinary income at your marginal federal rate. It is not subject to preferential long-term capital gains treatment. Consult a tax adviser about strategies such as holding real estate debt investments inside a self-directed IRA to defer taxation.
What is the minimum investment to start with real estate debt funds for accredited investors?
Minimum investment thresholds vary by platform and offering. Many individual loan investments on private lending platforms start at $5,000–$25,000. Pooled fund structures may have different minimums. Finresi's current offering details and minimums are listed directly on each investment opportunity page after you complete verification.
Keep reading
 Insights
Inside Finresi’s Underwriting: The 25-Point Checklist for Every Loan
Finresi stress-tests every loan against a 25-point underwriting checklist spanning borrower credit, property valuation, loan structure, market conditions, and exit strategy. Here is how each category shapes your real estate debt investment risk profile.
 Insights
Beyond LTV: 5 Other Risk Factors to Analyze in a Real Estate Loan Note
Loan-to-value ratio is just the starting point. Learn the five additional real estate debt investment risk factors, including borrower financial strength, market absorption, and exit strategy viability, that determine whether a loan note performs or fails.
