Insights · September 21, 2026
The Finresi Secondary Market: How We Provide a Liquidity Option for Investors
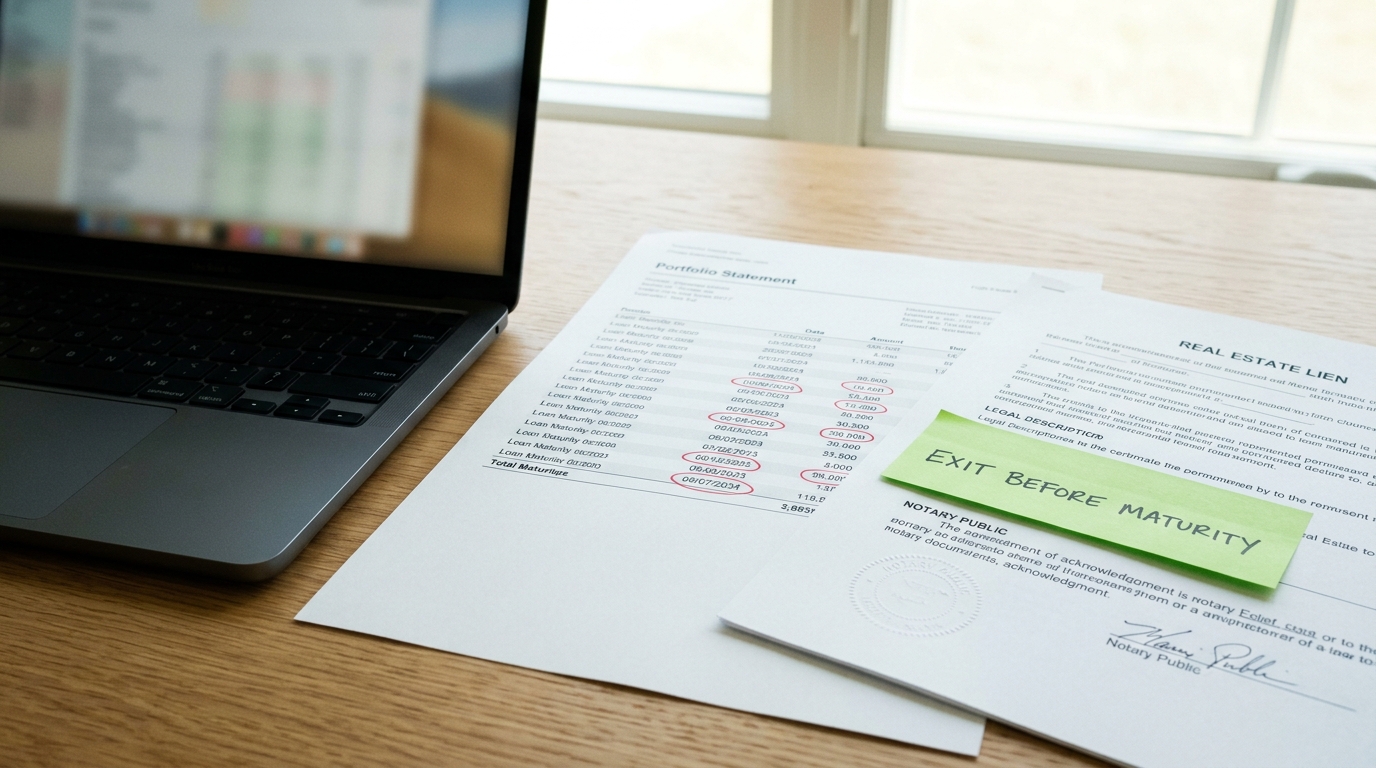
The Finresi secondary market gives accredited investors a structured pathway to exit real estate debt positions before loan maturity, addressing the single most common objection to private credit: illiquidity. Rather than locking capital for an entire loan term, investors can list holdings for peer transfer, recovering principal and accrued interest based on actual market demand.
Why Liquidity Is the Central Risk in Real Estate Debt Investing
Real estate debt investments generate returns through interest payments on loans secured by physical property. That security is genuine: in default scenarios, lenders hold a lien against an asset with recoverable value. But the trade-off is time. A bridge loan might run 12–24 months. A construction loan can extend further. During that window, your capital is deployed and not immediately accessible.
For accredited investors building a diversified passive income portfolio, this creates a planning problem. Market conditions shift. Personal liquidity needs arise. An opportunity in another asset class emerges. Without a secondary market mechanism, the only options are to wait for loan maturity or accept that a private credit allocation is structurally inflexible.
Finresi treats this not as an unavoidable feature of the asset class but as a solvable problem. The secondary market is the solution, and understanding how it works changes the practical calculus around sizing a real estate debt allocation.
How the Finresi Secondary Market Operates
The secondary market on Finresi functions as a peer-to-peer transfer system. An existing investor who wants to exit a position lists their loan interest for sale on the platform. Prospective buyers, who must also be verified accredited investors, can review the listing and elect to acquire the position.
Here is the step-by-step process:
- Listing initiation: The selling investor selects the loan position they want to exit from their portfolio dashboard and submits a listing request. The listing displays the outstanding principal balance, the remaining loan term, the interest rate, the loan-to-value ratio, and the underlying collateral details.
- Price determination: Sellers set an asking price that reflects the remaining principal and any accrued interest. The platform does not impose a discount mandate, but sellers who price competitively relative to the loan's remaining return profile attract buyers faster.
- Buyer review: Buyers on the secondary market access the same underwriting data that was available at origination, including property appraisal, borrower financials, and Finresi's internal credit assessment. This transparency is intentional: buyers take on the same risk profile the original investor accepted, so they need the full picture.
- Transfer execution: Once a buyer commits, Finresi facilitates the legal transfer of the investment interest. The seller receives proceeds. The buyer steps into the position and begins receiving interest payments for the remainder of the loan term.
- Settlement timing: Transfer settlement typically completes within 3–5 business days of a successful match, giving the exiting investor reasonably fast access to recovered capital.
One important clarification: secondary market liquidity is demand-dependent. Finresi does not guarantee buyback or redemption. If no buyer elects to acquire a listed position, the seller remains in the investment until maturity or until a buyer appears. Investors should size positions with this contingency in mind rather than treating the secondary market as an unconditional exit.
Underwriting Criteria That Support Secondary Market Confidence
A secondary market only functions if buyers trust the asset they are acquiring. That trust is built at origination, through Finresi's underwriting process. Buyers on the secondary market are not taking a leap of faith: they are evaluating a loan that has already passed a structured review. Understanding what that review covers explains why secondary market positions attract genuine buyer interest.
Finresi applies the following underwriting criteria to every loan at origination:
- Loan-to-value ratio: Finresi targets LTV ratios that preserve a meaningful equity cushion for lenders. Lower LTV at origination means greater collateral protection if a borrower defaults and the property must be liquidated.
- Borrower experience and track record: Real estate loans involve operational risk, not just collateral value. Finresi evaluates borrower experience with comparable project types, prior completion history, and financial strength before approving a loan.
- Property valuation: All loans are supported by independent third-party appraisals. Finresi does not rely solely on automated valuations for assets above minimum thresholds.
- Exit strategy feasibility: Every loan has an identified repayment source: refinance, property sale, or end-buyer takeout. Finresi stress-tests exit strategies against realistic market scenarios rather than peak-case assumptions.
- Title and legal review: Title insurance and lien position verification are required for all loans. First-lien position is the standard; second-lien exposure, where permitted, is disclosed explicitly.
When a secondary market buyer reviews a listing, they are reviewing assets that have passed all five of these filters. That upfront diligence is what makes the secondary market a functional tool rather than a distressed-asset clearinghouse.
Risk Factors Investors Must Understand Before Using the Secondary Market
Sophisticated investors do not conflate liquidity optionality with liquidity certainty. The Finresi secondary market reduces illiquidity risk but does not eliminate it. A complete risk picture includes the following considerations:
| Risk Factor | Nature of the Risk | Mitigation Strategy |
|---|---|---|
| Demand-dependent exit | No buyer may be available when you list | Size positions so you can hold to maturity without disruption |
| Price negotiation | Buyers may expect a yield premium to absorb a shorter remaining term | List early in the loan term when remaining return is more attractive |
| Borrower default risk | The underlying loan can default regardless of secondary market activity | Rely on LTV cushion and collateral; review Finresi's default resolution process |
| Market value decline | Collateral property value may fall, reducing recovery in default | Favor loans with conservative LTV at origination |
| Platform concentration | All positions are administered through Finresi's infrastructure | Diversify across loan types, geographies, and platforms where appropriate |
The practical guidance here is to treat the secondary market as a contingency mechanism rather than an active trading tool. Build a portfolio of real estate debt positions sized so that, in a worst case where no buyers appear, holding each to maturity remains financially comfortable. The secondary market then provides upside optionality rather than required infrastructure.
How to Maximize Secondary Market Effectiveness as an Investor
Investors who use the secondary market most effectively apply a few consistent practices from the moment they originate a position, not at the point they decide to sell.
Diversify across loan maturities. A portfolio with positions maturing at 6 months, 12 months, 18 months, and 24 months creates natural liquidity events throughout the holding period. Dependence on the secondary market decreases when maturity laddering provides regular capital return from loan repayments.
Document your entry rationale. Buyers on the secondary market ask the same questions you asked at origination. Loans with clean, well-documented underwriting rationales move faster. Finresi provides all original underwriting data in the listing, but investors who select well-underwritten loans at origination are selecting assets that will be easier to exit later.
List positions before distress, not because of it. The optimal time to use the secondary market is when your personal liquidity needs change, not when the underlying loan shows stress. A performing loan with a strong collateral position and 8 months remaining is an attractive secondary market acquisition. A loan under watch-list status is a much harder sell.
Monitor platform activity. Secondary market depth varies with overall platform volume. As Finresi's investor base grows, secondary market liquidity improves because the pool of potential buyers expands. Investors who stay engaged with platform activity have a more accurate read on current secondary market conditions when they need to use them.
Comparing Real Estate Debt Liquidity to Other Private Asset Classes
| Asset Class | Typical Lock-Up Period | Secondary Market Availability | Redemption Guarantee |
|---|---|---|---|
| Finresi Real Estate Debt | 6–24 months per loan | Yes, peer-to-peer transfer | No; demand-dependent |
| Private Equity Funds | 7–10 years | Limited; specialized secondary funds | No |
| Real Estate Syndications | 3–7 years | Rare; sponsor-dependent | No |
| Interval Funds (Real Estate) | Quarterly redemption windows | Fund-level redemption only | Partial; subject to fund limits |
| REITs (Public) | None | Exchange-traded | Market liquidity only |
Real estate debt through Finresi occupies a practical middle ground: shorter lock-up periods than most private alternatives, a genuine secondary market mechanism, and collateral-backed downside protection that public REITs do not provide at the position level.
Finresi Secondary Market FAQ
Is the Finresi secondary market guaranteed to find a buyer for my position?
No. The secondary market is a peer-to-peer transfer platform. Finresi facilitates the listing and transaction process but does not guarantee a buyer will be available for every position. Investors should structure allocations so they can hold positions to maturity if no secondary market exit is available.
What information does a secondary market buyer receive about the loan?
Buyers receive the complete origination underwriting package: property appraisal, borrower financials, loan-to-value ratio, lien position, remaining term, interest rate, and Finresi's internal credit assessment. Transparency at the listing level is what enables buyers to make informed acquisition decisions.
Can I list a loan position that is underperforming or in default?
Positions in default or under formal workout are generally not eligible for secondary market listing. The secondary market is designed for performing loans where the primary motivation to sell is the investor's liquidity need, not loan performance concerns.
How long does it typically take to complete a secondary market transfer once a buyer commits?
Settlement typically completes within 3–5 business days of a confirmed buyer commitment. Finresi handles the legal transfer documentation and notifies both parties when the transaction is finalized.
Does selling on the secondary market affect the interest rate or terms for the buyer?
The underlying loan terms, including the interest rate and maturity date, do not change. The buyer steps into the existing investment at the agreed transfer price and receives interest payments for the remainder of the original loan term. Any negotiation between seller and buyer affects only the transfer price, not the loan's contractual terms.
Keep reading
 Insights
Understanding Loan-to-Value (LTV): A Core Metric for Debt Investors
Loan-to-value ratio is the cornerstone metric for assessing real estate debt investment risk. This guide breaks down how LTV works, why the equity cushion matters, and what accredited investors should watch for in underwriting.
 Insights
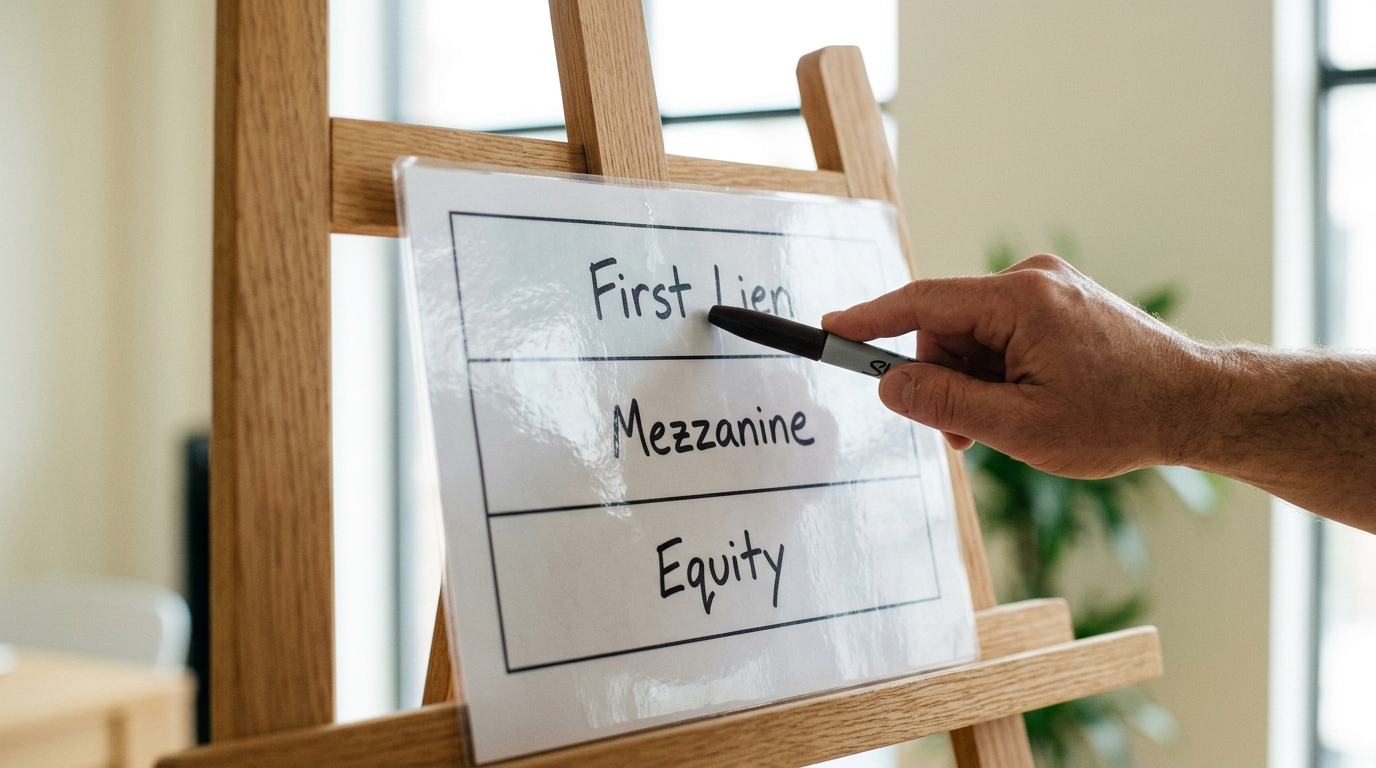
First-Lien Position: How Collateral Protects Your Principal Investment
First-lien position places your investment at the front of the repayment queue, giving you priority over all junior creditors in a default. Understanding this structure is essential for evaluating real estate debt investment risk.
