Insights · September 17, 2026
First-Lien Position: How Collateral Protects Your Principal Investment
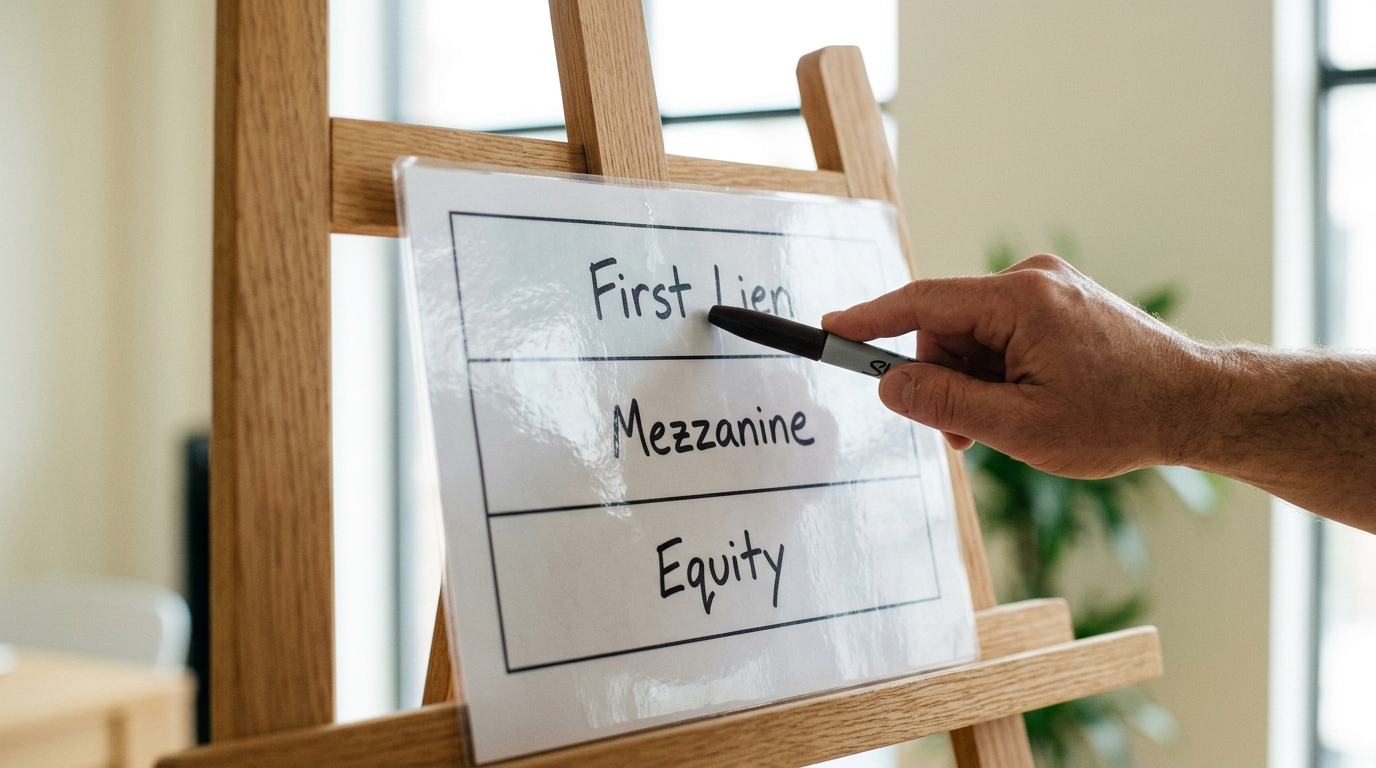
First-lien position means your investment sits at the front of the repayment queue: if a borrower defaults, the first-lien lender recovers principal before any junior debt holder, equity partner, or unsecured creditor receives a dollar. For accredited investors evaluating real estate debt investment risk, that structural priority is the single most consequential variable in the capital stack.
What First-Lien Position Actually Means in a Default Scenario
A first-lien mortgage is recorded against a property at closing. That recording creates a legal claim that travels with the title. When a borrower stops paying, the first-lien holder initiates foreclosure and, upon completion, takes ownership of the collateral or directs its sale. Proceeds flow to the first-lien holder until the outstanding balance, accrued interest, and allowable fees are fully satisfied. Only then does any remaining value reach second-position lenders or equity holders.
Consider a concrete example. A property is appraised at $1,000,000. A first-lien loan is originated at $650,000, establishing a loan-to-value (LTV) ratio of 65%. If the borrower defaults and the property sells at foreclosure for $780,000 after carrying costs and legal fees, the first-lien investor recovers 100% of principal plus a significant portion of accrued interest. A second-lien holder owed $100,000 would receive the remaining $130,000. An equity investor receives nothing until both debt positions are cleared. That waterfall structure is not a contractual courtesy; it is enforced by state foreclosure law.
The gap between the loan balance and the collateral value is called equity cushion, and it is the investor's primary buffer against loss. A 65% LTV loan carries a 35% cushion, meaning property values would need to decline more than 35% before the lender faces a principal impairment, net of liquidation costs.
Underwriting Criteria That Determine Real Collateral Strength
First-lien position is a legal protection. Its practical value depends entirely on underwriting quality. Sophisticated real estate debt platforms, including Finresi, apply layered criteria before a loan is approved for investor capital.
Independent appraisal and valuation review. A third-party licensed appraiser produces a full narrative appraisal on every Finresi loan. The internal underwriting team then stress-tests that value by reviewing comparable sales on a trailing 12-month basis, applying a liquidation discount of 10–15% to simulate a distressed sale, and confirming that the resulting net value still exceeds the loan amount.
Borrower credit and track record assessment. A borrower's capacity to service debt and execute the business plan reduces the probability of default, which is just as important as recovery rates. Finresi evaluates FICO scores, liquidity reserves, and verified experience with comparable projects. A developer with five completed fix-and-flip renovations presents a materially different risk profile than a first-time borrower, and loan terms reflect that difference.
Property condition and inspection. Collateral value is only real if the asset is in the condition the appraisal assumes. Every Finresi loan includes a physical inspection report. For construction and renovation loans, draws against a reserve fund are approved only after inspection confirms completed work, preventing capital from being disbursed ahead of verified milestones.
Title insurance and lien searches. A first-lien position can be compromised by undisclosed prior liens, mechanic's liens, or tax encumbrances. Finresi requires lender's title insurance on every transaction, and a full lien search is conducted at origination. This step protects the recorded priority position that underpins the entire risk framework.
Comparing Risk Profiles: First-Lien Debt vs. Other Capital Stack Positions
| Position | Repayment Priority | Typical LTV Exposure | Return Profile | Loss Scenario |
|---|---|---|---|---|
| First-lien debt | First | 55%–70% of appraised value | Fixed interest, 8%–12% annualized (current market) | Requires property value decline beyond equity cushion before principal is impaired |
| Second-lien / mezzanine debt | Second | 70%–85% of appraised value | Higher fixed or blended interest, 12%–16% | Subordinated to first lien; absorbs losses once equity cushion is exhausted |
| Preferred equity | Third | 85%–90% of appraised value | Fixed preferred return plus potential upside | Entire equity cushion must be wiped before preferred equity is impaired |
| Common equity | Last | Residual interest above debt | Uncapped upside; project-dependent | First position to absorb losses from day one |
The table above illustrates a foundational trade-off in real estate investing: higher position in the capital stack means lower return potential and lower loss exposure. First-lien debt investors accept a capped yield in exchange for structural seniority and collateral backing. That trade-off is precisely what makes first-lien positions attractive for passive income strategies where capital preservation is a primary objective.
Due Diligence Layers Finresi Applies Before Every Loan
Mitigating risk in real estate lending requires a documented, repeatable process, not judgment calls made loan by loan. Finresi's due diligence framework operates in three sequential phases.
Phase 1: Pre-screening. The borrower submits a loan application, property details, and a project summary. Finresi's origination team screens the submission against minimum criteria: property type eligibility, geographic market limits, maximum LTV thresholds, and minimum borrower liquidity requirements. Loans that fail any single criterion do not advance. The majority of submitted applications are declined at this stage.
Phase 2: Full underwriting. Approved applications enter full underwriting. This phase includes the third-party appraisal, title search, physical inspection, borrower background check, and financial statement review. The underwriting team builds a stress scenario model that tests the loan against a 20% property value decline and a six-month extended carrying period. A deal must perform acceptably in that scenario to receive credit committee approval.
Phase 3: Closing and post-close monitoring. Closing is handled by a licensed title company or real estate attorney. After closing, Finresi monitors each loan through its term by tracking property tax payment status, insurance policy renewal, and, for construction loans, draw request documentation. Early signals of borrower distress are identified through systematic monitoring rather than reactive complaint handling.
This three-phase process is not window dressing. It directly determines the quality of collateral backing investor capital, and the rigor applied at each phase is the mechanism through which first-lien protection translates from legal theory into practical capital preservation.
Geographic Concentration and Market Risk
First-lien position protects against borrower-specific default risk. It does not fully insulate investors from regional market risk. If a portfolio is concentrated in a single metropolitan market and that market experiences a sharp correction, multiple loans can see collateral values decline simultaneously, even if each individual loan was properly underwritten at origination.
Finresi addresses this through geographic diversification across its loan portfolio. Investors accessing the platform gain exposure to loans across multiple states and property types rather than concentrating in a single market cycle. Within an individual loan, maximum LTV limits create a buffer sized to absorb localized price corrections. In markets with higher observed price volatility, Finresi applies more conservative LTV caps, typically 60% or below, to account for larger potential drawdowns.
What Accredited Investors Should Verify Before Committing Capital
Understanding the framework is necessary but not sufficient. Before deploying capital into any real estate debt investment, accredited investors should request and review specific documentation.
- The actual appraisal report, not just the summarized LTV figure
- The title insurance commitment confirming first-lien priority with no undisclosed encumbrances
- The inspection report or construction draw schedule for renovation and new construction loans
- The borrower's demonstrated project history, including completed deals with verifiable outcomes
- The platform's stated default rate and average recovery rate on loans that entered workout over the past 24 months
- The legal structure of the investment vehicle: are investors direct mortgage holders, or beneficiaries of a fund or participation agreement?
The legal structure question matters significantly. Direct mortgage participation gives investors a recorded interest in the property. Fund structures and participation agreements introduce an additional layer of counterparty risk at the platform level. Finresi discloses the specific legal structure of each offering in the loan-level documentation provided to investors before commitment.
Real Estate Debt Investment Risk FAQ
What happens to my investment if a borrower defaults on a Finresi loan?
Finresi initiates the foreclosure process as the first-lien holder. The property is either sold through foreclosure proceedings or taken into REO (real estate owned) status and subsequently liquidated. Investor principal recovery depends on the net sale proceeds relative to the outstanding loan balance. Because Finresi loans are originated at LTV ratios of 55%–70%, the equity cushion must be fully exhausted before investor principal is at risk of impairment.
Is first-lien position guaranteed to protect my principal?
First-lien position provides legal priority and a defined equity cushion, but no investment is without risk. Extreme property value declines, extended holding periods during foreclosure, or undisclosed liens that survive title review can reduce recovery. Finresi's underwriting, title insurance requirements, and LTV limits are designed to reduce these risks to levels consistent with the fixed return offered, but they do not eliminate them entirely.
What LTV ratios does Finresi typically originate at?
Finresi targets maximum LTV ratios of 65%–70% on stabilized properties and applies more conservative limits of 60% or below in higher-volatility markets or on construction loans where value is not yet fully realized. Specific LTV figures are disclosed in each loan's offering documents.
How do I qualify as an accredited investor to access Finresi's loans?
Under SEC Regulation D, an accredited investor meets at least one of these criteria: net worth exceeding $1,000,000 excluding primary residence, annual income exceeding $200,000 individually (or $300,000 jointly with a spouse) in each of the two most recent years with a reasonable expectation of the same in the current year, or holding a Series 7, 65, or 82 securities license in good standing. Finresi verifies accreditation status before granting access to loan offerings.
How does real estate debt investing compare to owning rental property for passive income?
Direct rental ownership delivers income through rent collection and long-term appreciation, but requires active management, exposes the investor to tenant risk, and ties up large amounts of capital in a single illiquid asset. Real estate debt investing through Finresi delivers fixed interest income without property management responsibilities, with principal backed by collateral rather than dependent on rental market performance. The trade-off is that debt investors do not participate in property appreciation above the loan balance.
Keep reading
 Insights
Inside Finresi’s Underwriting: The 25-Point Checklist for Every Loan
Finresi stress-tests every loan against a 25-point underwriting checklist spanning borrower credit, property valuation, loan structure, market conditions, and exit strategy. Here is how each category shapes your real estate debt investment risk profile.
 Insights
What is an Accredited Investor in 2026? The Official Requirements & How to Verify
Accredited investor status unlocks private real estate debt funds targeting 8–12% annual returns. Learn the 2026 SEC requirements and how to verify your eligibility before you invest.
