Insights · September 30, 2026
The Finresi Underwriting Scorecard: A Transparent Look at Our 25-Point Due Diligence Process
Finresi's 25-Point Underwriting Scorecard Explained
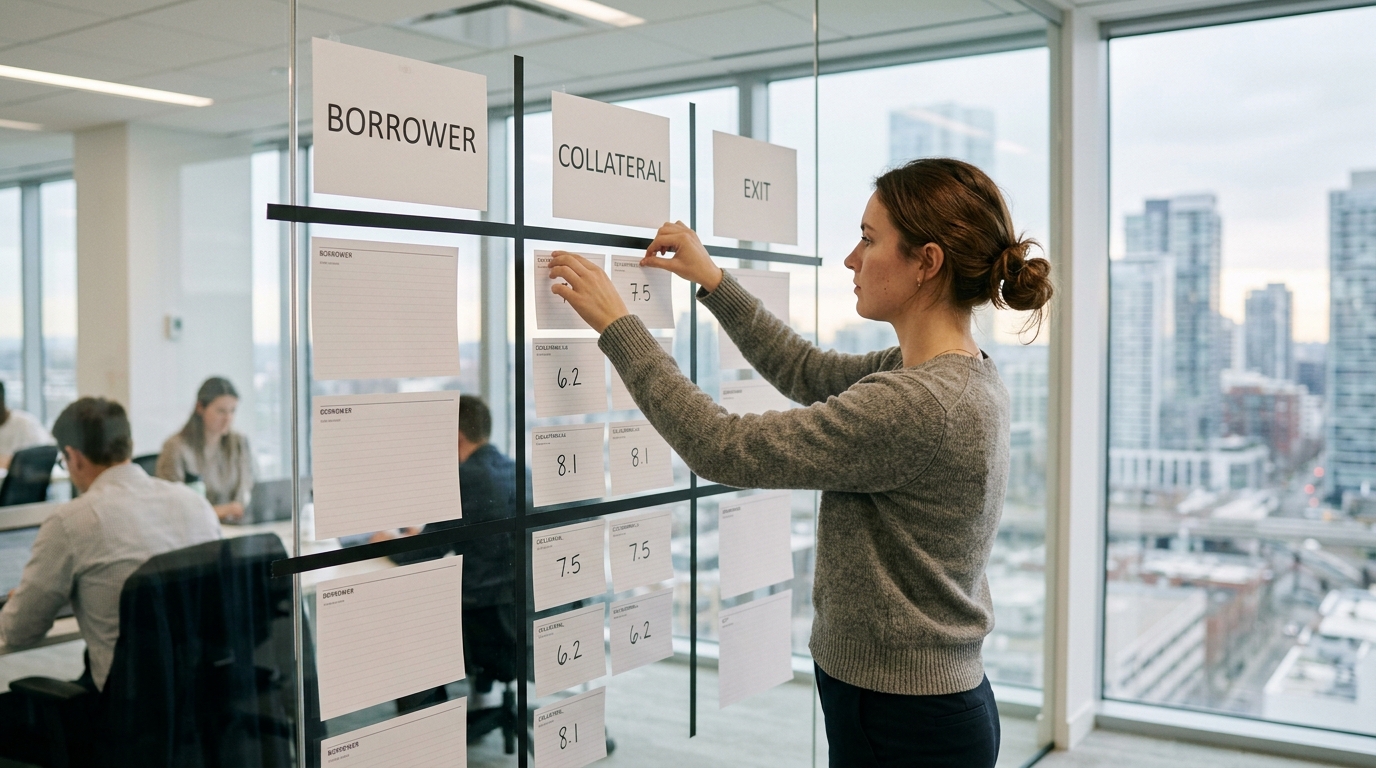
Finresi evaluates every real estate loan opportunity against a structured 25-point scorecard before any deal reaches the investor platform. The scorecard assigns weighted scores across five risk categories: borrower quality, property fundamentals, loan structure, market conditions, and exit viability. A deal must clear a minimum composite threshold to proceed. This article explains what each category measures, how the scoring works in practice, and what it means for accredited investors seeking predictable passive income from real estate debt.
Why Underwriting Discipline Is the Core of Real Estate Debt Investing
Real estate debt investment risk is fundamentally different from equity risk. As a lender, your upside is capped at the contracted interest rate, but your downside exposure is bounded by the collateral securing the loan. That asymmetry makes collateral quality and borrower reliability the two variables that matter most. Strong underwriting shifts the probability distribution of outcomes toward consistent coupon payments and principal return, while weak underwriting allows loan losses to erode returns even when the broader market cooperates.
Sophisticated investors understand that yield alone is not a sufficient signal of a good deal. A 14% return on a poorly collateralized bridge loan in a declining submarket is far less attractive than a 10% return on a senior secured position backed by a property with strong comparable sales and a creditworthy sponsor. Finresi's 25-point scorecard forces every deal through the same analytical lens, removing the cognitive shortcuts that cause lenders to rationalize marginal opportunities.
Category 1: Borrower Quality (6 Points)
The borrower category carries the highest individual weight because loan performance tracks closely with sponsor experience and financial capacity. Finresi examines six specific factors in this category:
- Track record: Verified completion of comparable projects within the last five years, with documentation of cost-to-completion ratios and sale timelines.
- Liquidity reserves: Minimum of 10% of the total loan amount held in liquid assets post-close, independent of the project budget.
- Credit history: No bankruptcies in the preceding seven years and no unresolved judgments against the borrowing entity.
- Entity structure: Single-purpose entity usage is scored higher because it reduces cross-collateral risk from unrelated borrower obligations.
- Guarantor strength: Personal guarantee backed by verifiable net worth of at least 1.25x the loan amount.
- Prior lender relationships: References checked directly with previous capital providers, not self-reported.
A first-time fix-and-flip borrower with thin liquidity will score low in this category, which raises the threshold required from other categories for the deal to proceed. This calibration prevents new sponsors from carrying deals that experienced sponsors with proven execution records could reasonably support.
Category 2: Property Fundamentals (5 Points)
Collateral quality is assessed through five property-level criteria that form the backbone of due diligence for real estate loans. An independent appraisal or broker price opinion is required for every transaction, supplemented by Finresi's internal comparable analysis.
- As-is value: The property's current market value must support a loan-to-value ratio within program guidelines before any renovation is factored in.
- After-repair value (ARV): Projected ARV is stress-tested at a 10% reduction against the borrower's submitted comparable sales to account for market movement during the project term.
- Property condition: A third-party inspection report categorizes deferred maintenance and structural issues. Material deficiencies require holdbacks or completion reserves.
- Title and encumbrance review: Finresi holds a first-lien position on all loans. Any existing liens, easements, or encumbrances that cannot be cleared before funding result in automatic disqualification.
- Property type and marketability: Single-family residences and small multifamily properties score higher than niche commercial assets in the same market because of broader buyer demand at exit.
Category 3: Loan Structure (5 Points)
A sound loan structure aligns the borrower's incentives with the lender's capital protection goals. The five structural points Finresi scores are directly tied to underwriting criteria for investment performance under stress conditions.
- Loan-to-cost (LTC): Total loan amount as a percentage of total project cost, including acquisition and renovation. Finresi targets a maximum LTC of 85% across the portfolio.
- Loan-to-ARV: The ratio of the loan to the stabilized or resale value. Senior positions are limited to 70% of ARV, which preserves a meaningful equity cushion against value declines.
- Draw schedule structure: Construction and renovation funds are released in tranches tied to verified project milestones rather than disbursed upfront. This materially reduces completion risk.
- Prepayment and extension provisions: Deals are scored on the clarity and fairness of extension terms. Borrowers who need additional time must meet performance milestones before any extension is granted.
- Debt service coverage or interest reserve: For longer-term loans, a funded interest reserve covering a minimum of three months of payments is required where the project does not generate current income.
Category 4: Market Conditions (5 Points)
Mitigating risk in real estate lending requires understanding the market into which the borrower will eventually sell or refinance. Finresi analysts review the following five market-level indicators for each deal:
- Days on market trends: Rising days on market in the subject property's zip code reduces the score, as slower absorption increases the probability that the borrower will need an extension.
- Price per square foot trajectory: Declining price per square foot trends over the trailing six months are flagged and require the ARV assumption to be adjusted downward.
- Supply pipeline: Active permit data is reviewed to assess whether new competing inventory is likely to hit the market during the loan term.
- Employment and income trends: Markets with single-employer dependency or recent significant layoff announcements receive lower market scores regardless of current price data.
- Investor activity concentration: Submarkets where more than 30% of recent transactions were investor-to-investor sales receive a lower score because those prices may not reflect true end-buyer demand.
Category 5: Exit Viability (4 Points)
Every real estate loan has a defined maturity date, and the borrower's ability to exit either through a sale or a refinance is the final checkpoint in the scorecard. The four exit viability points address the most common failure modes seen in short-term real estate lending.
- Primary exit strategy feasibility: The borrower must demonstrate a realistic sale timeline based on current absorption rates, not peak-market assumptions.
- Secondary exit strategy: Finresi requires identification of a secondary exit path. For fix-and-flip loans, this typically means demonstrating that the stabilized property would qualify for conventional or agency financing if the sale takes longer than projected.
- Refinance qualification analysis: For bridge loans on income-producing properties, a debt service coverage ratio analysis under the expected refinance terms is performed at origination.
- Borrower's exit execution history: Borrowers who have experienced prior maturity defaults or forced extensions on other lenders' loans are scored negatively, even if those loans were ultimately resolved without loss.
How the Composite Score Works in Practice
Each of the 25 points is scored on a 0-to-4 scale, producing a maximum composite score of 100. Deals scoring below 70 are declined without exception. Deals scoring between 70 and 79 require a credit committee review and typically require structural enhancements, such as a lower LTC, a larger interest reserve, or additional collateral, before approval. Deals scoring 80 and above proceed through final legal and title review on an expedited basis.
This tiered structure creates a consistent record of underwriting decisions that investors can audit. Rather than relying on relationship-driven lending or subjective sponsor enthusiasm, Finresi's process produces a documented rationale for every approval or decline. That documentation is available to investors reviewing individual loan opportunities on the platform.
What This Means for Accredited Investors Building Passive Income
When you invest in a real estate loan through Finresi, you are not relying on a single underwriter's judgment or a verbal commitment from a borrower. You are placing capital behind a documented scoring process that has evaluated hundreds of discrete risk variables across five categories. The scorecard does not eliminate risk, but it makes risk visible, measurable, and consistently managed across every deal in the portfolio.
For accredited investors comparing real estate debt investing to other passive income strategies, the scorecard represents a structural advantage. It provides a repeatable framework that produces consistent underwriting standards regardless of deal volume or market conditions, which is precisely the discipline that separates institutional lending from informal private money.
Finresi Underwriting FAQ
What is the minimum score a deal must achieve to be listed on the Finresi platform?
All deals must achieve a minimum composite score of 70 out of 100 on Finresi's 25-point underwriting scorecard. Deals scoring between 70 and 79 require additional credit committee review and structural enhancements before approval. Deals scoring below 70 are declined without exception regardless of sponsor relationship or deal size.
How does Finresi protect investors if a borrower defaults before the loan matures?
All Finresi loans are secured by a first-lien position on the collateral property. In a default scenario, the lien structure gives investors priority claim over the asset ahead of all unsecured creditors. The maximum loan-to-ARV of 70% is designed to preserve a meaningful equity buffer that supports principal recovery through a distressed sale or foreclosure proceeding.
Are the underwriting criteria the same for fix-and-flip loans and bridge loans on income-producing properties?
The five scoring categories apply to all loan types, but the specific criteria within each category are calibrated to the loan type. Bridge loans on income-producing properties include a debt service coverage ratio analysis in the exit viability category, while fix-and-flip loans place greater weight on absorption rate and comparable sale data in the market conditions category.
How often does Finresi update its underwriting criteria to reflect current market conditions?
Finresi's credit committee reviews the scorecard weighting and specific criteria on a quarterly basis. Market condition thresholds, including days-on-market benchmarks and price trend sensitivity, are updated more frequently when regional market data signals significant shifts. Any changes to scorecard criteria are applied prospectively and do not affect the stated terms of loans already funded on the platform.
Does a high scorecard result guarantee that a loan will not experience payment delays?
No underwriting process eliminates the possibility of payment delays or default. A high composite score reflects a strong probability of successful performance based on documented evidence at origination. Borrower circumstances, property market conditions, and construction costs can change after funding. Finresi maintains active loan monitoring and regular draw inspections to identify emerging issues early and work with borrowers on structured solutions before a default event occurs.
Keep reading
 Insights
The 'Missing Middle' Housing Gap: A Persistent Opportunity for Debt Investors
The chronic undersupply of 2–50 unit residential properties across major U.S. metros is fuelling sustained borrower demand. Private lenders who understand the missing middle have a multi-year runway in the best markets for real estate debt.
 Insights
Residential vs. Commercial Real Estate Debt: A 2026 Risk/Return Profile
In 2026, real estate debt investors must choose between residential and commercial loans, each with distinct risk mechanics and return profiles. This breakdown compares collateral, underwriting, and liquidity across both sectors.
