Insights · September 28, 2026
Residential vs. Commercial Real Estate Debt: A 2026 Risk/Return Profile
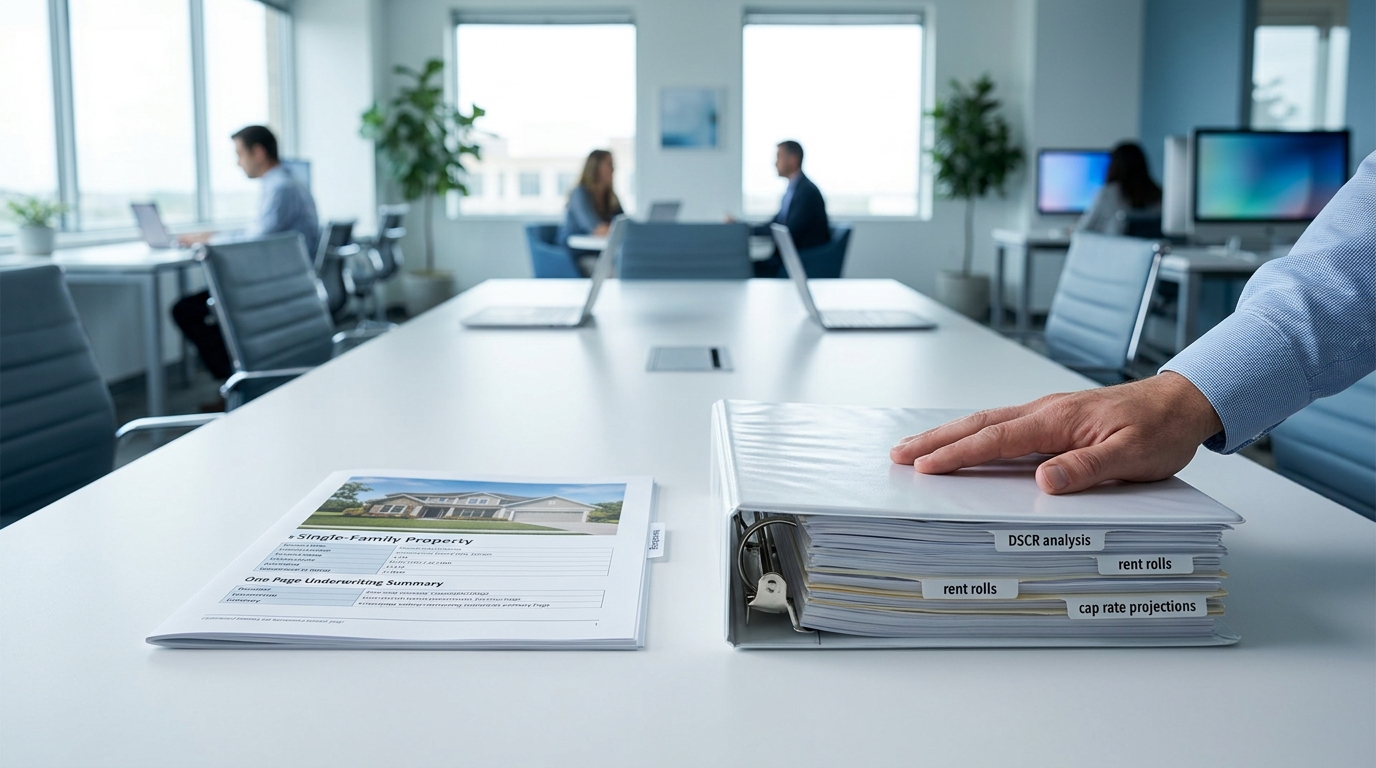
In 2026, real estate debt investors face a clear structural choice: allocate capital toward residential loans (fix-and-flip, bridge, small multi-family) or toward commercial real estate debt (office, retail, large mixed-use). Each sector carries distinct risk mechanics, return profiles, and liquidity timelines. Finresi's underwriting focuses primarily on residential and small multi-family debt, a deliberate positioning based on collateral predictability, loan cycle speed, and current market fundamentals.
How Residential and Commercial Real Estate Debt Differ at the Loan Level
The difference between residential and commercial real estate debt is not simply property type. It runs through every layer of underwriting, from how collateral is valued to how a borrower's income is assessed to how quickly a distressed loan can be resolved.
Residential loans, particularly fix-and-flip and bridge loans on 1–4 unit properties, are underwritten against after-repair value (ARV). A lender evaluates what the property will sell for once renovations are complete, then sizes the loan to a loan-to-value ratio that protects principal if the borrower defaults. Loan terms are short: typically 6–18 months. If a borrower fails to perform, the lender forecloses on a single-family asset with a deep pool of owner-occupant buyers and retail investors ready to absorb it. Resolution timelines are faster, and exit values are supported by retail demand, not cap rate compression.
Commercial real estate debt is structured against net operating income and capitalization rates. A lender models stabilized cash flows, applies a debt service coverage ratio (DSCR) floor (commonly 1.20x–1.25x), and prices the loan against a spread to benchmark rates. The collateral is a cash-flow business, not a physical asset with standalone resale value to a broad buyer pool. When office occupancy drops or a retail anchor tenant leaves, the collateral value can fall sharply and the buyer pool for that distressed asset is narrow, meaning longer resolution timelines and higher workout costs.
The 2026 Risk Profile: Where Each Sector Stands
Office commercial real estate debt continues to carry elevated risk in 2026. Hybrid and distributed work patterns have stabilized at levels that leave significant vacancy in secondary urban markets. Lenders who extended office loans in 2021–2022 at peak valuations are now working through refinancing gaps as properties fail to support debt at current interest rates. The commercial real estate debt market in this segment rewards only the most selective, senior-secured lenders with deep workout capacity.
Retail commercial debt is bifurcated. Neighborhood grocery-anchored retail has held up well, while discretionary retail in enclosed malls remains structurally impaired. Lenders active in retail must underwrite tenant credit and lease term risk as carefully as they underwrite the property itself.
Residential real estate in 2026 presents a different picture. Housing inventory remains constrained in most major metros. The lock-in effect from lower-rate mortgages has kept existing homeowners in place, and new single-family construction has not kept pace with household formation. This supply constraint supports resale values, which directly protects the collateral position of fix-and-flip lenders. Borrowers can sell completed renovations into a market with buyer demand, which means shorter hold periods and cleaner loan resolution.
Small multi-family (2–8 units) sits at the intersection of residential fundamentals and income-producing property. Rental demand in urban and suburban infill markets remains strong. These assets are financed under residential lending standards in many states, use residential appraisal methodologies, and attract a broader buyer pool than institutional commercial product. For debt investors, small multi-family offers a yield premium over single-family without the complexity and concentration risk of large commercial.
Return Profiles: What Lenders Are Actually Earning
Across these sectors, loan yields vary materially based on risk, term, and leverage. The table below compares approximate return and risk characteristics across residential and commercial debt segments in 2026.
| Loan Type | Typical Loan Term | Approximate Gross Yield | Primary Risk Factor | Collateral Liquidity |
|---|---|---|---|---|
| Fix-and-flip (1–4 unit) | 6–12 months | 9%–12% | Renovation cost overrun, ARV miss | High (retail buyer pool) |
| Residential bridge loan | 12–18 months | 8%–11% | Refinance availability at maturity | High |
| Small multi-family (2–8 unit) | 12–24 months | 8%–10.5% | Vacancy, tenant credit | Moderate-high |
| Commercial bridge (office/retail) | 12–36 months | 9%–13% | Occupancy, cap rate expansion, tenant risk | Low-moderate |
| Large commercial construction | 18–36 months | 10%–14% | Completion risk, lease-up, rate exposure | Low |
The yield premium on commercial debt is real, but it compensates for tangible risks: longer resolution timelines, illiquid collateral, and complex workout situations that require dedicated asset management resources most individual investors do not possess. Residential debt yields in the 9%–12% range, with short loan cycles and liquid collateral, represent a strong risk-adjusted case for most accredited investors seeking passive income.
Best Markets for Real Estate Debt in 2026
Not all geographies carry equal opportunity or risk. Finresi's underwriting targets markets where three conditions converge: active real estate investor activity, sufficient transaction volume to validate ARV estimates, and regulatory frameworks that allow efficient foreclosure if a loan defaults.
Sun Belt metros including Atlanta, Dallas-Fort Worth, Charlotte, and Tampa continue to generate substantial fix-and-flip and small multi-family loan volume. Population in-migration has sustained housing demand, renovation spreads remain attractive because of the price gap between distressed and retail-ready inventory, and foreclosure timelines in these states are among the shortest in the country.
Mid-Atlantic and Southeast secondary cities (Raleigh, Richmond, Jacksonville, Nashville) have shown consistent deal flow for bridge and fix-and-flip loans. These markets avoid the extreme competition that compresses investor margins in coastal gateway cities, while still providing sufficient transaction volume for reliable ARV comparables.
Markets to approach with caution in the current environment include coastal gateway cities where property tax and regulatory costs have compressed renovation margins, and Midwest markets with declining population bases where resale velocity has slowed. In these areas, even well-underwritten loans face longer absorption timelines if foreclosure becomes necessary.
How Finresi Applies This Analysis to Loan Underwriting
Finresi structures its investment offerings around first-lien residential and small multi-family real estate loans. Every loan in the portfolio is secured by a recorded first-lien deed of trust or mortgage, meaning investors have a senior claim on the underlying collateral before any other creditor. Loan-to-value ratios are set based on as-is or after-repair value determined by licensed appraisers or broker price opinions from local market specialists.
The underwriting process evaluates four factors on every loan: borrower experience and track record, property-level collateral quality and marketability, market-level exit demand, and project-level budget feasibility. For fix-and-flip loans, Finresi reviews contractor bids, renovation scopes, and draw schedules before funding. Construction draws are released in stages against verified completed work, which limits capital exposure at any single point in a project.
Investors on the Finresi platform participate in individual loans or across a managed portfolio, earning interest income tied directly to the underlying loan yields. Because loan terms are short (typically 6–18 months), capital recycles regularly. That cycle speed matters for passive income strategies: investors receive returns more frequently and have more opportunities to redeploy capital than they would in a long-duration commercial real estate debt position.
Finresi does not pursue large commercial office, retail, or construction loans. That boundary is intentional. The platform is designed for accredited investors who want predictable income from collateral they can understand, not yield chasing in complex commercial structures that require institutional-grade workout capabilities.
Residential vs. Commercial Real Estate Debt FAQ
What makes residential real estate debt lower risk than commercial debt?
Residential collateral (single-family homes, small multi-family properties) has a broad buyer pool that includes owner-occupants, retail investors, and buy-and-hold landlords. When a residential loan defaults, the lender can sell the foreclosed property into that market relatively quickly. Commercial properties depend on a narrower pool of institutional buyers and are valued based on tenant income, which can collapse if occupancy falls. The combination of higher collateral liquidity and shorter loan terms makes residential debt structurally less risky for most passive investors.
What returns can accredited investors expect from residential real estate loans in 2026?
Fix-and-flip and residential bridge loans are currently generating gross yields in the 9%–12% range. Net investor returns depend on the platform's fee structure and any loan losses, but senior-secured residential loans with conservative LTV ratios (typically 65%–75% of ARV) have historically shown low loss rates, allowing investors to retain the majority of the stated yield as actual income.
Which geographic markets offer the best real estate lending opportunities in 2026?
Sun Belt metros (Atlanta, Dallas-Fort Worth, Charlotte, Tampa) and Southeast secondary cities (Raleigh, Jacksonville, Nashville) offer the strongest combination of investor deal flow, renovation margin, and efficient foreclosure timelines. These markets support accurate ARV comparables and provide active buyer pools for completed renovations.
How does Finresi protect investor capital in its real estate loans?
Finresi takes first-lien positions on all loans, sets loan-to-value ratios at 65%–75% of after-repair value, and releases construction draws in stages against verified completed work. These structural protections mean the property must lose substantial value before investor principal is at risk. Borrowers are also screened for renovation experience and project feasibility before any loan is funded.
Do I need to be an accredited investor to access Finresi's real estate debt offerings?
Yes. Finresi's investment offerings are structured for accredited investors, defined in 2026 as individuals with a net worth exceeding $1 million (excluding primary residence) or annual income above $200,000 ($300,000 jointly) in each of the two most recent years with a reasonable expectation of the same going forward. Institutional investors and entities meeting SEC accreditation standards are also eligible to participate.
Keep reading
 Insights
Top 5 Regional Markets for Bridge Loan Investing in 2026
The strongest bridge loan markets in 2026 share tight inventory, active fix-and-flip demand, and experienced borrower pools. Here are the five regions where real estate debt investors are finding the most durable lending conditions.
 Insights
Analyzing the Spread: What Is the Risk Premium on Private Real Estate Debt in 2026?
Private real estate debt is offering a risk premium of 200–400 basis points above Treasuries in 2026. Learn how Federal Reserve policy shapes those spreads and what it means for fixed income alternatives investors.
