Insights · October 28, 2026
Laddering Real Estate Notes: A Strategy for Consistent Cash Flow and Reinvestment
Laddering Real Estate Notes Delivers Predictable Cash Flow for Accredited Investors
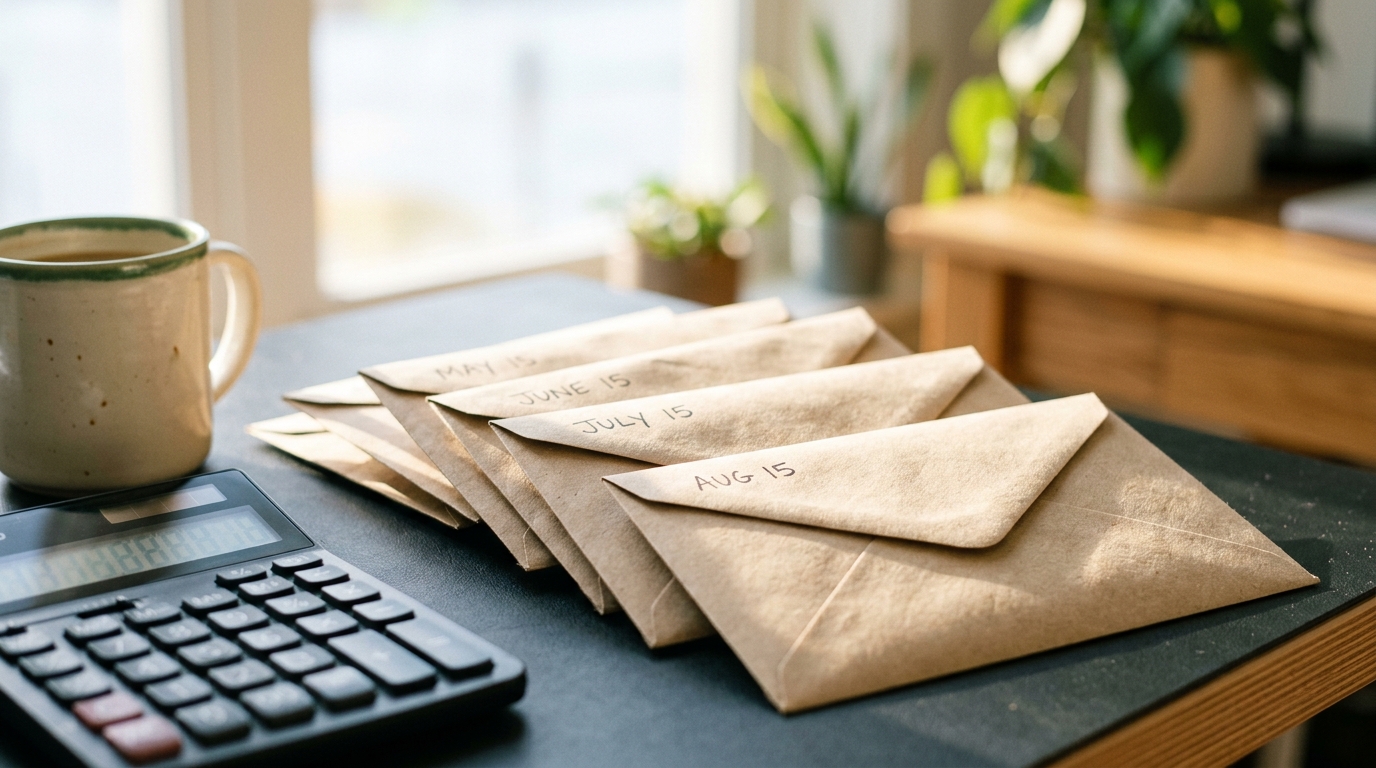
Note laddering in real estate debt is a structured portfolio approach where an accredited investor staggers loan maturities across multiple time horizons, typically 6, 12, 18, and 24 months, so that capital becomes available for reinvestment on a rolling basis rather than all at once. The result is a passive income portfolio that generates regular liquidity events without forcing the investor to time the market or accept idle cash drag.
For high-net-worth individuals who hold concentrated positions in equities or private equity, real estate debt laddering offers an alternative asset allocation that operates independently of public market volatility. This guide covers the mechanics of building a ladder, the trade-offs between short and long-duration notes, and the specific steps accredited investors can take to integrate this strategy into a broader wealth plan.
What Note Laddering Actually Means in Practice
The term "laddering" originates in fixed-income bond investing, where investors buy bonds with sequential maturity dates to reduce reinvestment risk. Applied to real estate debt, the same principle governs how you deploy capital across individual loans or loan participations.
Imagine deploying $200,000 across eight positions of $25,000 each, with maturities spread across every quarter for two years. When the first note matures at month six, you receive principal plus earned interest. That capital immediately rolls into a new note at whatever rate and term currently fits the market. You never experience a full portfolio reset, and you always have active positions earning yield.
This matters practically because real estate lending markets shift. Bridge loan rates, loan-to-value requirements, and borrower demand all fluctuate. A ladder allows you to capture improving rates on new positions while existing positions continue paying at the rates you locked in earlier. It is the structural equivalent of dollar-cost averaging, applied to yield rather than price.
Short-Duration vs. Long-Duration Notes: Specific Trade-offs
Every position in a ladder occupies a specific place on the duration spectrum. The choice is not arbitrary; each end of the spectrum carries distinct risk and return characteristics that shape how the ladder performs over time.
| Characteristic | Short-Duration Notes (3–9 months) | Long-Duration Notes (12–24 months) |
|---|---|---|
| Typical annual yield range | 8%–10% | 10%–13% |
| Reinvestment frequency | High: capital recycles 2–4 times per year | Low: capital is committed for extended periods |
| Rate risk exposure | Low: you reprice quickly if rates rise | Moderate: locked into current rate for longer |
| Cash flow predictability | Moderate: maturities cluster if ladder is shallow | High: extended accrual supports income planning |
| Borrower profile | Fix-and-flip, quick bridge scenarios | Ground-up construction, stabilized bridge loans |
| Default resolution complexity | Lower: shorter timelines reduce exposure | Higher: more time for project risk to develop |
A well-constructed ladder does not concentrate entirely at either end. Investors seeking liquidity prioritize positions in the 6–12 month range and use longer positions to capture yield premiums on a smaller portion of allocated capital. Investors focused on income stability weight the 12–24 month range more heavily, accepting lower reinvestment frequency in exchange for predictable monthly or quarterly interest payments.
Building the Ladder: Allocation Mechanics for a Diversified Portfolio
Start with a target capital allocation to real estate debt as a share of your overall alternative asset allocation. For most accredited investor portfolios that follow diversification strategies for high net worth goals, real estate debt represents 10%–25% of total investable assets, alongside private equity, venture, and commodities. Within that sleeve, the ladder structure determines how individual capital is distributed.
A practical framework for a $300,000 real estate debt allocation:
- Rung 1 (0–6 months): $75,000 across 3 positions maturing within the next two quarters. These provide near-term liquidity and the option to exit the ladder or redeploy if your financial needs change.
- Rung 2 (6–12 months): $75,000 across 3 positions. This middle rung captures slightly higher yields than short-term notes while still recycling capital within a year.
- Rung 3 (12–18 months): $75,000 across 3 positions. Typically backed by construction or transitional bridge loans with first-lien security, offering the yield premium that justifies the longer commitment.
- Rung 4 (18–24 months): $75,000 across 3 positions. The longest duration rung, held for maximum yield and income planning certainty. Reserve this rung for the most conservatively underwritten loans in the pipeline.
As each rung matures, you do not simply replace it with an identical position. You assess current market conditions, your portfolio's existing duration exposure, and any near-term liquidity requirements before selecting the new note's term. This active management at reinvestment points is what separates a ladder from a passive buy-and-hold real estate debt strategy.
Risk Mitigation Built Into the Ladder Structure
Note laddering is not just a yield optimization tool; it is a risk management architecture. Because capital matures in pieces rather than all at once, a single loan default or extension represents a fraction of total portfolio exposure, never a portfolio-level event.
Three specific risk controls reinforce the ladder's structural benefit:
Geographic diversification across rungs. Allocate each rung's positions across different metro markets. A slowdown in one regional market affects a single position, not your entire Rung 3 allocation. Real estate debt in a portfolio performs best when the underlying collateral is spread across markets with different economic drivers.
Loan-to-value discipline by rung. Apply stricter LTV thresholds on longer-duration notes. A 65% LTV ceiling on 18–24 month positions provides greater equity cushion over the longer hold period, protecting principal if property values soften. Shorter rungs can accommodate up to 70%–75% LTV because the exposure window is narrower.
First-lien priority as a baseline. Across all rungs, prioritize first-lien debt positions. Second-lien and mezzanine positions carry substantially higher loss-given-default ratios and belong, if at all, in a small satellite allocation rather than inside the core ladder structure.
Integrating Real Estate Debt Laddering with Your Broader Wealth Plan
A real estate note ladder does not operate in isolation. It interacts with your tax position, liquidity planning, and income replacement goals in ways that require coordination with your financial and tax advisors.
On the income side, interest payments from real estate notes are typically taxed as ordinary income. Investors in high federal brackets may want to hold note positions inside a self-directed IRA or self-directed 401(k) to defer taxation on earned interest. The ladder structure works inside these vehicles the same way it does in a taxable account: maturities stagger, capital reinvests, and the compounding effect accelerates over time within the tax-advantaged wrapper.
On the liquidity side, the ladder's rolling maturity schedule functions as a built-in liquidity calendar. If you know a capital need arises in 14 months, structure a Rung 2 position to mature slightly ahead of that date. This precision is not available with REITs, which require selling shares at market price, or with private equity funds, which lock capital for seven to ten years with limited flexibility. Real estate debt laddering gives you a passive income portfolio that also doubles as a planned liquidity schedule.
For investors comparing this strategy against other income-producing alternatives, the practical advantages come into focus clearly:
- vs. dividend equities: Real estate notes carry senior secured collateral; dividend payments carry no asset backing and can be cut without notice.
- vs. REITs: Notes provide fixed contractual returns; REIT distributions vary with operating performance and carry equity-level volatility.
- vs. money market funds: Notes yield materially more, though with lower liquidity and higher minimum investment thresholds appropriate for an accredited investor portfolio.
- vs. private equity: Shorter durations, more frequent liquidity events, and senior-secured positioning reduce the risk profile significantly.
Getting Started on Finresi
Finresi provides accredited investors with access to first-lien real estate debt positions across multiple property types and geographies, with stated maturities that make ladder construction straightforward. Each listing includes the loan term, rate, LTV, and collateral details needed to place individual positions into the correct rung of your ladder. Because positions are available across a range of durations, you can build all four rungs from a single platform without sourcing loans through multiple channels.
Minimum investment thresholds are set to allow meaningful diversification across rungs without requiring outsized capital concentration in any single position. Review current offerings on the Finresi investment platform to identify positions that fit your target duration, yield requirement, and geographic diversification goals.
Real Estate Note Laddering FAQ
How many positions do I need to build an effective real estate note ladder?
A minimum of eight to twelve positions across four maturity rungs gives you meaningful diversification without making the portfolio unmanageable. Fewer than six positions concentrates too much capital in individual loans; more than twenty positions across a single debt sleeve can create administrative complexity without proportionate risk reduction.
What accredited investor requirements apply to real estate note investing?
Under SEC Regulation D, accredited investors must meet at least one of these thresholds: individual net worth exceeding $1 million excluding primary residence, individual income exceeding $200,000 in each of the two most recent years with expectation of the same in the current year, or joint income with a spouse exceeding $300,000 under the same standard. Professional certifications including Series 7, Series 65, and Series 82 licenses also qualify an individual regardless of income or net worth.
What happens to my ladder position if a borrower defaults?
On a first-lien note, the lender or platform initiates foreclosure proceedings against the underlying collateral. Recovery depends on the property's current value relative to the outstanding loan balance. A position underwritten at 65% LTV has a 35% equity buffer before the lender absorbs losses, which provides substantial protection in most market scenarios. The maturity on the defaulted position extends through the resolution process, which is why shorter-duration rungs should not carry the full weight of the ladder's risk exposure.
Can I build a real estate note ladder inside a self-directed IRA?
Yes. Self-directed IRAs and self-directed Solo 401(k) plans permit investment in real estate debt, including individual loan positions and participations. All interest income and principal repayments return to the retirement account tax-deferred or tax-free depending on the account type. The ladder mechanics remain identical; the only difference is that the custodian holds the positions on behalf of the retirement account rather than directly in your name.
How does real estate note laddering compare to buying a REIT for passive income?
REITs offer daily liquidity and lower minimums but deliver equity-level return volatility and distributions that fluctuate with property operating performance. A real estate note ladder delivers contractually fixed interest at rates that are set at origination, backed by senior-secured collateral, and unaffected by occupancy fluctuations or rental market cycles. The trade-off is lower liquidity during the note term. Investors who can commit capital for six to twenty-four month windows consistently achieve better risk-adjusted income from a well-constructed ladder than from a comparable REIT allocation.
Keep reading
 Insights
From Signup to First Return: A Step-by-Step Walkthrough of Investing with Finresi
Finresi takes accredited investors from signup to passive income in as few as five business days. This step-by-step guide covers eligibility, funding, loan selection, and return collection in full detail.
 Insights
How Accredited Investors Use Real Estate Debt to Stabilize Equity-Heavy Portfolios
Equity-heavy accredited investor portfolios carry hidden concentration risk and unreliable income. Real estate debt investing adds contractual cash flows and reduces correlation to volatile equity markets.
