Insights · October 12, 2026
Finresi Fund vs. Individual Notes: Which Path is Right for Your Portfolio?
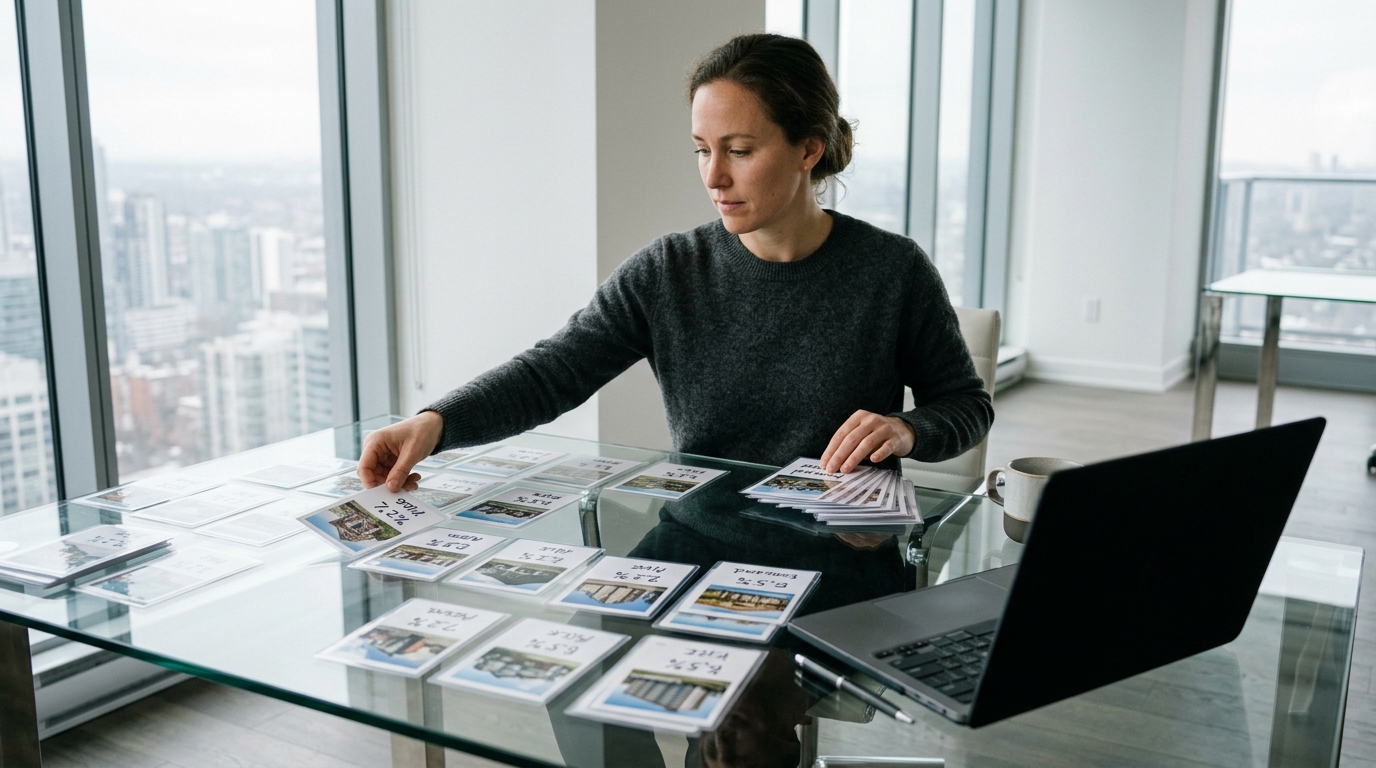
The Finresi Fund pools accredited investor capital into a diversified portfolio of real estate debt positions, targeting consistent passive income without requiring investors to select, underwrite, or manage individual loans. For investors weighing the fund against note-by-note investing, the core distinction is this: the fund trades deal-selection control for automatic diversification and lower operational overhead.
What the Finresi Fund Actually Is
The Finresi Fund is a real estate debt fund structured to deploy capital across multiple loan types, including fix-and-flip bridge loans, ground-up construction loans, and stabilized rental property loans. Rather than allocating capital to a single borrower on a single asset, the fund spreads exposure across dozens of positions at any given time. Each underlying loan is secured by a first-lien deed of trust on real property, meaning the fund holds senior secured status in the capital stack.
The fund is available exclusively to accredited investors, defined under SEC Regulation D as individuals with a net worth exceeding $1 million excluding primary residence, or annual income of at least $200,000 (or $300,000 joint) in each of the two most recent years with a reasonable expectation of the same in the current year. Finresi verifies accredited status before any capital is accepted, a standard compliance requirement under Rule 506(c) offerings.
Target annualized returns for the fund are communicated at the time of subscription and are tied to the blended yield of the underlying loan portfolio. Because Finresi focuses on short-duration loans, typically 6–24 months in term, the portfolio turns over regularly, allowing the fund manager to adjust loan mix in response to credit conditions and rate environments without locking capital into multi-year illiquid positions.
How Individual Note Investing Works on the Finresi Platform
When an investor selects individual notes through Finresi, they review specific loan opportunities, each with a deal summary covering the property address, loan-to-value ratio, borrower profile, loan term, and projected interest rate. The investor then commits capital to that specific loan. Their return is tied to that single borrower's repayment performance, and their principal is secured by the lien on that specific property.
Individual note investing gives investors direct visibility into exactly where their money sits. An investor can choose to concentrate in one geography, one loan type, or one risk tier. That selectivity is genuinely valuable for investors who have real estate underwriting knowledge and want to apply it. Someone with deep familiarity with Texas single-family rehab projects, for example, can choose to only fund that type of deal and reasonably expect their domain knowledge to add value.
The trade-off is concentration risk. If a borrower defaults and the collateral sale does not fully recover principal, that loss sits entirely with the investors in that note. A single bad loan can meaningfully impair the returns on a thinly diversified note portfolio. Managing that risk requires either large note portfolios (typically 20 or more positions) or careful deal selection, both of which require time and expertise.
Finresi Fund vs. Individual Notes: A Direct Comparison
| Feature | Finresi Fund | Individual Notes |
|---|---|---|
| Diversification | Automatic, across dozens of loans | Manual, depends on number of notes selected |
| Minimum investment | Set at the fund level (typically higher) | Set per note (typically lower per position) |
| Investor involvement | Passive: no loan selection required | Active: investor reviews and selects each deal |
| Default exposure | Spread across full portfolio | Concentrated in selected loans only |
| Return visibility | Blended portfolio yield | Exact rate tied to each specific loan |
| Liquidity | Subject to fund redemption terms | Subject to individual loan maturity |
| Tax reporting | Single K-1 or 1099 from fund | Separate reporting per note |
| Ideal investor profile | Passive income seekers, portfolio diversifiers | Hands-on investors with underwriting knowledge |
The Diversification Advantage and Why It Matters in Real Estate Debt
Diversification in real estate debt investing is not just about spreading across more loans. It means reducing the impact of any single default event on the overall portfolio. In a fund with 40 active loans, a single default with a 50% loss severity would reduce total portfolio returns by roughly 1.25 percentage points, a manageable drag. In a note portfolio of 5 loans, the same event wipes out 10% of principal before any recoveries are factored in.
The Finresi Fund also diversifies across loan types and geographies, which matters because real estate markets are highly localized. A softening in one metro's fix-and-flip demand does not necessarily affect bridge loan performance in a different region with different supply dynamics. A concentrated individual note investor in one market does not have that buffer.
Additionally, the fund's deal sourcing is continuous. Fund managers deploy incoming capital and reinvest repaid principal into new loans as they originate, maintaining the portfolio's diversification level without requiring investor action. An individual note investor who receives loan repayments must actively find new notes to redeploy capital, or accept periods of idle cash drag.
When Individual Notes Outperform the Fund
There are real scenarios where selecting individual notes produces better risk-adjusted outcomes than the fund. An investor with underwriting expertise who identifies a loan at a favorable loan-to-value ratio in a market they know well can lock in a higher rate on a well-secured position. That precision is not available through the fund, which blends returns across all positions.
Individual notes also work well for investors building toward a specific income target. If the yield on a particular note matches a known cash flow need, funding that note creates a predictable income stream for the loan term. There is no distribution variability tied to portfolio-wide performance or fund manager allocation decisions.
Short-term capital deployment is another use case. If an investor has $50,000 available for 9 months and finds a single note matching that timeline, they can deploy precisely and exit cleanly at maturity. Fund redemption terms may not offer the same precision.
Liquidity Considerations for Both Paths
Neither the Finresi Fund nor individual real estate notes are liquid instruments in the way publicly traded securities are. Both paths require investors to accept the illiquidity premium that comes with private real estate debt, and that premium is a core reason yields in this asset class exceed those of comparable-duration investment-grade bonds.
For the fund, liquidity is governed by the fund's redemption policy. Most private real estate debt funds offer periodic redemption windows, quarterly or semi-annually, subject to available liquidity. Investors should read the fund's offering documents carefully to understand notice periods and any gates that may apply during periods of elevated redemption requests.
Individual notes mature at a fixed date, providing a known exit point. However, if a borrower extends or defaults, that exit date shifts. Finresi's loan servicing team manages extensions and workout situations, but investors in individual notes should underwrite each position assuming the loan may run to its maximum extended term before returning principal.
Tax Treatment: Simplicity vs. Control
The Finresi Fund issues a single annual tax document (typically a Schedule K-1 for partnership-structured funds, or a 1099 for certain fund structures). That simplicity reduces accounting complexity significantly, particularly for investors who would otherwise hold 15–20 individual notes, each generating its own interest income reporting.
Individual note investors receive separate interest income reports for each position. For high-volume note investors, this creates meaningful tax preparation overhead. However, direct note ownership also allows investors to track basis, losses, and recoveries at the position level, which can be advantageous if a specific note generates a realized loss that offsets other income.
Investors holding either path inside a self-directed IRA or Solo 401(k) should confirm with their plan custodian that the investment structure is permitted. Both fund interests and individual real estate notes are generally eligible for self-directed retirement accounts, though fund-level UBTI (unrelated business taxable income) disclosure warrants review with a tax advisor.
Choosing the Right Path for Your Portfolio
The right choice depends on three factors: available capital, desired involvement level, and existing portfolio construction. Investors deploying $50,000 or less into real estate debt for the first time get better risk management through the fund because building a 20-note individual portfolio at that capital level is not feasible without excessive concentration. Investors deploying $250,000 or more have enough capital to build a reasonably diversified individual note portfolio while still maintaining meaningful position sizes per loan.
Investors who want zero ongoing involvement in loan selection belong in the fund. Investors who want to apply real estate knowledge and build customized exposure belong in individual notes. Many sophisticated investors use both: the fund as a core allocation for passive, diversified exposure, and a smaller satellite allocation to individually selected notes where they have conviction on a specific deal.
Finresi Fund FAQ for Accredited Investors
What is the minimum investment in the Finresi Fund?
The minimum investment amount is disclosed in the fund's offering documents and is set at the fund level. Prospective investors should contact Finresi directly to confirm the current minimum, as it may differ from minimums on individual notes offered through the platform.
How does the Finresi Fund generate returns for investors?
The fund earns interest income from the pool of first-lien real estate loans it holds. That income, net of fund expenses and management fees, is distributed to investors according to the fund's distribution schedule. Returns reflect the blended yield of all active loan positions at any given time.
What happens to my investment if a borrower in the fund defaults?
A default by one borrower affects only a fraction of the total portfolio, limiting its impact on overall fund performance. Finresi's asset management team pursues recovery through collateral liquidation, and because loans are secured by first-lien real property, recovery rates depend on the underlying asset value relative to the outstanding loan balance.
Can I invest in both the Finresi Fund and individual notes simultaneously?
Yes. Many Finresi investors use a blended approach: the fund provides passive, diversified exposure as a core holding, while individual notes allow targeted positioning in specific deals. There is no requirement to choose one path exclusively.
Is the Finresi Fund suitable for retirement accounts?
Fund interests held in self-directed IRAs or Solo 401(k) accounts are generally permissible, but investors must confirm eligibility with their custodian and review any UBTI implications with a qualified tax advisor before investing retirement capital in the fund.
Keep reading
 Insights
The Finresi Fund: A Deep Dive into Diversified Real Estate Debt Investing in 2026
The Finresi Fund is a pooled real estate debt vehicle giving accredited investors diversified exposure to private loans, including fix-and-flip, bridge, and construction financing. It offers passive income through interest distributions while spreading default risk across an entire loan portfolio.
 Insights
A Look Inside a Live Deal: Anatomy of a Fix-and-Flip Loan Investment
Fix-and-flip loan investments give accredited investors a first lien position on short-term real estate debt, typically yielding 8–12% annually. Walk through a live deal to see exactly how capital is deployed, protected, and returned.
