Insights · October 8, 2026
A Look Inside a Live Deal: Anatomy of a Fix-and-Flip Loan Investment
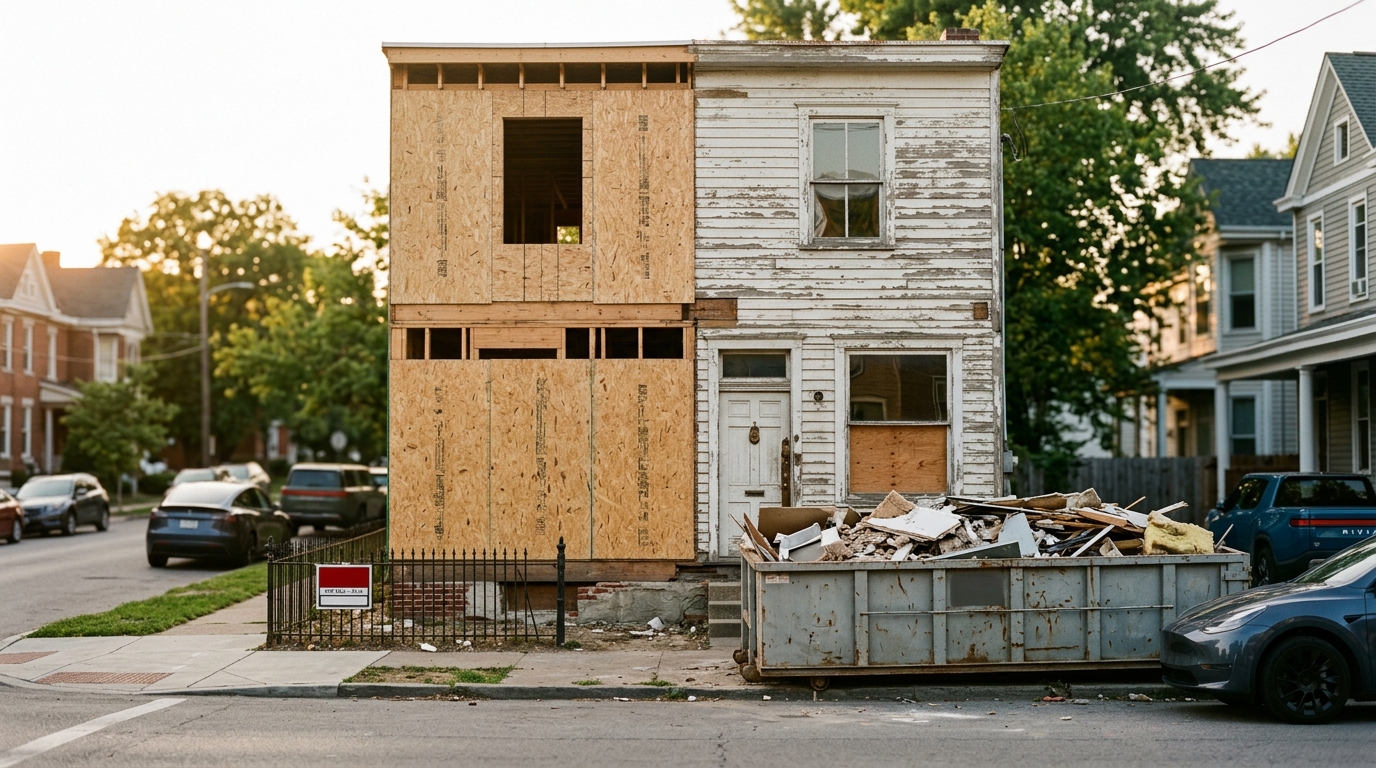
A fix-and-flip loan investment gives accredited investors a first lien position on a short-term real estate debt instrument, typically yielding 8%–12% annually, secured by a physical property at a loan-to-value (LTV) ratio of 65%–75%. Understanding the full anatomy of one live deal reveals exactly how capital is deployed, protected, and returned.
What a Fix-and-Flip Loan Actually Is
A fix-and-flip loan is a short-term, asset-backed bridge loan extended to a real estate investor who purchases a distressed or undervalued property, renovates it, and sells it, typically within 6–18 months. The lender (in this context, the platform and its investor base) holds the first lien on the property. That lien is the foundational protection: if the borrower defaults, the lender has the legal right to foreclose and recover principal from the asset sale before any other creditor receives a dollar.
This structure places real estate debt investing in a fundamentally different risk category than equity investing. Equity investors profit only if the project succeeds. Debt investors receive their return from day one through interest accrual, regardless of how much appreciation the borrower ultimately captures. The upside is capped, but so is the downside.
For accredited investors seeking passive income without property management obligations, fix-and-flip loan investments deliver consistent, defined cash flows backed by tangible collateral.
Walking Through a Live Deal: The Key Components
Every fix-and-flip loan has a set of measurable parameters. Here is how a representative deal on the Finresi platform breaks down:
- Property type: Single-family residential, 3 bed / 2 bath, located in a high-demand suburban market
- Purchase price: $285,000
- Renovation budget: $60,000 (held in a controlled draw schedule)
- After-repair value (ARV): $425,000 (established by a licensed, independent appraiser)
- Loan amount: $255,750 (representing 60% of ARV)
- Interest rate: 10.5% per annum
- Loan term: 12 months with a 3-month extension option
- Origination fee: 2 points, paid by borrower at closing
- Investor yield: 9.0% net annualized return
Each of these figures is not arbitrary. The 60% LTV creates a 40% equity cushion: the property would need to lose more than $169,000 in value before investor principal is at risk. That buffer absorbs renovation cost overruns, market softness, and liquidation costs in a worst-case scenario.
How the Renovation Draw Schedule Protects Capital
One of the most misunderstood protections in fix-and-flip lending is the draw schedule. The borrower does not receive the full renovation budget at closing. Instead, funds are released in tranches, typically 3–5 draws, tied to verified completion milestones. A licensed inspector confirms that each phase of work is complete before the next draw is authorized.
This mechanism eliminates a common risk vector: a borrower who takes construction capital and misappropriates it before the property is improved. When Finresi underwrites a deal, the renovation budget is held in a controlled escrow account. The investor's capital finances an improving asset, not a promise to improve one.
From an investor's perspective, this means the collateral value increases throughout the loan term. A property appraised at $285,000 pre-renovation steadily approaches its $425,000 ARV as work proceeds. The LTV ratio improves over the life of the loan, not deteriorates.
Underwriting Standards: What Gets Filtered Before You See a Deal
Accredited investors reviewing a deal on Finresi see a curated set of loans. What they do not see is the volume of deals that did not pass underwriting. The filtering process is where risk management is actually earned.
A standard underwriting review for a fix-and-flip loan covers:
- Borrower track record: Minimum of 3–5 completed flips with documented sale records. First-time borrowers are not funded.
- Independent appraisal: ARV is established by a third-party appraiser, not the borrower's estimate or a broker price opinion alone.
- Comparable sales analysis: Active comps within a 1-mile radius and 90-day sale window. Markets with thin comparable sales data receive higher scrutiny.
- Title search and insurance: A clean title is required before funding. Title insurance is maintained throughout the loan term.
- Hazard insurance: The borrower carries a policy naming the lender as mortgagee. Coverage must equal or exceed the loan amount.
- Environmental and condition review: Properties with flagged environmental issues, significant structural deficiencies, or unpermitted work history are declined.
This filtering process is why real estate debt funds for accredited investors deliver more consistent outcomes than self-directed single-deal investing. The institutional underwriting infrastructure does the work that individual investors lack the resources or access to replicate.
First Lien Position: Why It Matters More Than Yield
When evaluating how to invest in real estate debt, most accredited investors anchor on yield first. That is the wrong starting point. Lien position is more important than the interest rate, because it determines the recovery hierarchy if a borrower defaults.
A first lien holder is paid before any second lien, mezzanine lender, or equity partner in a liquidation. In a foreclosure sale, proceeds cover the first lien balance and accrued interest before any other obligation is satisfied. A 9% yield in first lien position is structurally superior to a 13% yield in second lien position, because the risk-adjusted recovery rate on the 9% deal is dramatically higher.
Finresi structures all investor capital in first lien position. There is no subordination, no preferred equity stacking above the investor, and no mezzanine layer that would dilute recovery priority. This is the structural commitment that separates first lien position investing from higher-yield, higher-risk real estate debt products.
Deal Comparison: First Lien Fix-and-Flip vs. Common Alternatives
| Investment Type | Typical Yield | Lien / Seniority | Collateral | Liquidity | Investor Role |
|---|---|---|---|---|---|
| First Lien Fix-and-Flip Loan | 8%–12% net | First lien, senior secured | Physical real estate at 60%–75% LTV | Illiquid for loan term (6–18 months) | Passive income recipient |
| Real Estate Equity (Syndication) | 12%–20% projected (variable) | None (equity, junior to all debt) | Equity interest in asset | Illiquid, 3–7 year hold typical | Passive investor, profit-share dependent |
| Public REIT | 3%–6% dividend yield | No direct lien | None (indirect exposure) | Liquid (exchange-traded) | Passive shareholder |
| Second Lien Real Estate Debt | 12%–16% | Second lien, subordinate | Subordinate claim on real estate | Illiquid for loan term | Passive income, higher default exposure |
| Investment-Grade Corporate Bonds | 4%–6% (2026 market) | Unsecured or subordinated | None (credit-based) | Liquid (exchange-traded) | Passive bondholder |
What Happens at Loan Maturity
At the end of the loan term, the borrower has three standard exit paths: sell the property and repay the loan from proceeds, refinance into a long-term mortgage and repay the bridge loan, or in markets where ARV came in above projections, execute a cash-out refinance that nets the borrower a profit while clearing the debt. All three outcomes return principal and accrued interest to investors.
If the borrower requests an extension, Finresi evaluates the property's current status, progress toward ARV, and market conditions before approving. Extension periods are not automatic. They require demonstrated renovation progress and continued compliance with loan covenants. Extension fees, paid by the borrower, are often passed through to investors as additional income.
In the event of borrower default, Finresi initiates the foreclosure process and manages property disposition. The 40% equity cushion built into the deal structure gives the platform the ability to recover principal and most accrued interest even in a discounted sale. Investors in first lien position receive recovery proceeds before any other party.
How Finresi Structures Passive Participation
Passive real estate investing through Finresi does not require accredited investors to source deals, manage borrower relationships, or oversee construction draws. Investors review deal summaries that include property address (or market region), LTV, term, rate, borrower profile summary, and projected return. Capital is committed through the platform, and interest is distributed monthly or at maturity depending on the deal structure.
Minimum investment thresholds allow portfolio diversification across multiple loans, reducing single-asset concentration risk. An investor placing $100,000 across ten deals at $10,000 each has exposure to ten independent collateral positions, ten separate borrower relationships, and ten different market geographies. One underperforming loan does not compromise the portfolio's overall return profile.
Fix-and-Flip Loan Investment FAQ
What are the accredited investor requirements to participate in Finresi deals?
Accredited investors must meet SEC Regulation D standards: a net worth exceeding $1 million excluding primary residence, or annual income above $200,000 individually ($300,000 jointly) in each of the two most recent years with a reasonable expectation of the same in the current year. Finresi verifies accreditation before granting deal access.
How is the interest rate on a fix-and-flip loan determined?
The borrower's interest rate reflects the property's LTV ratio, the borrower's track record, the renovation complexity, and local market liquidity. Higher-LTV loans and first-time borrowers (who are excluded from the Finresi platform) carry higher rates. Investors receive a net yield after the platform's servicing fee, which is disclosed in each deal summary.
What happens if the borrower cannot sell the property at the expected ARV?
If the final sale price comes in below the projected ARV, the borrower still must repay the full loan balance from sale proceeds. Because the loan is sized at 60%–75% of ARV, a property selling at 80%–85% of its projected ARV still generates enough proceeds to repay principal and accrued interest in full. The equity cushion absorbs the gap.
Can investors exit a fix-and-flip loan position before maturity?
Fix-and-flip loan investments are illiquid for the loan term. They are not exchange-traded instruments. Investors should treat committed capital as locked for the full term, typically 6–18 months. This illiquidity premium is a structural reason why real estate debt yields exceed those of comparable liquid fixed-income instruments.
How does investing across multiple fix-and-flip loans reduce risk?
Diversification across multiple loans isolates individual deal risk. A single-loan default affects only the capital allocated to that specific investment. Spreading $100,000 across ten loans means a worst-case single default impacts 10% of the portfolio, not the full balance. Because each loan is independently collateralized by a separate property, the losses are not correlated in the way that equity positions in a single market sector would be.
Keep reading
 Insights
How to Become an Accredited Investor in 2026: The Complete Guide
Accredited investor status opens the door to private real estate debt funds offering first lien positions and passive income. This guide covers every qualification pathway and shows you exactly how to get started in 2026.
 Insights
The Finresi Fund vs. Individual Notes: Which Investment Is Right for You?
Finresi gives accredited investors two paths into real estate debt: a diversified pooled fund or individual first-lien notes. Here is how to choose the structure that fits your capital, risk tolerance, and hands-on preference.
